Buying Your First Home May Be Closer Than You Think
October 13, 2026
Articles for Buyers
October 13, 2026
Articles for Buyers
If you're renting and hoping to buy your first home, you've probably wondered how long it'll take to save enough money. Between rent, everyday expenses, and the cost of housing, coming up with a down payment can feel like a moving target.
But here's something many first-time homebuyers don't realize: You may not need to save nearly as much as you think.
Two decisions can make a substantial difference in how quickly you become a homeowner: choosing a more affordable home and understanding how much you actually need for a down payment.
And in Tallahassee, there are some local programs that may help make that first purchase even more attainable.
According to a 2026 Zillow study, it takes a typical U.S. household approximately 8.5 years to save for a 20% down payment on a mid-priced home.
After purchasing, Zillow estimates another 6.2 years before owning becomes more financially advantageous than renting. That's a combined 14.7 years.
That second figure is what's called the break-even point. It's when the overall financial benefits of ownership begin to outweigh what renting a comparable property would have cost over the same period, based on the study's assumptions.
But here's where the research gets interesting.
Zillow found that purchasing a starter home instead of a typical mid-priced home reduces that combined timeline to approximately 7.2 years nationally.
That's about half the time.
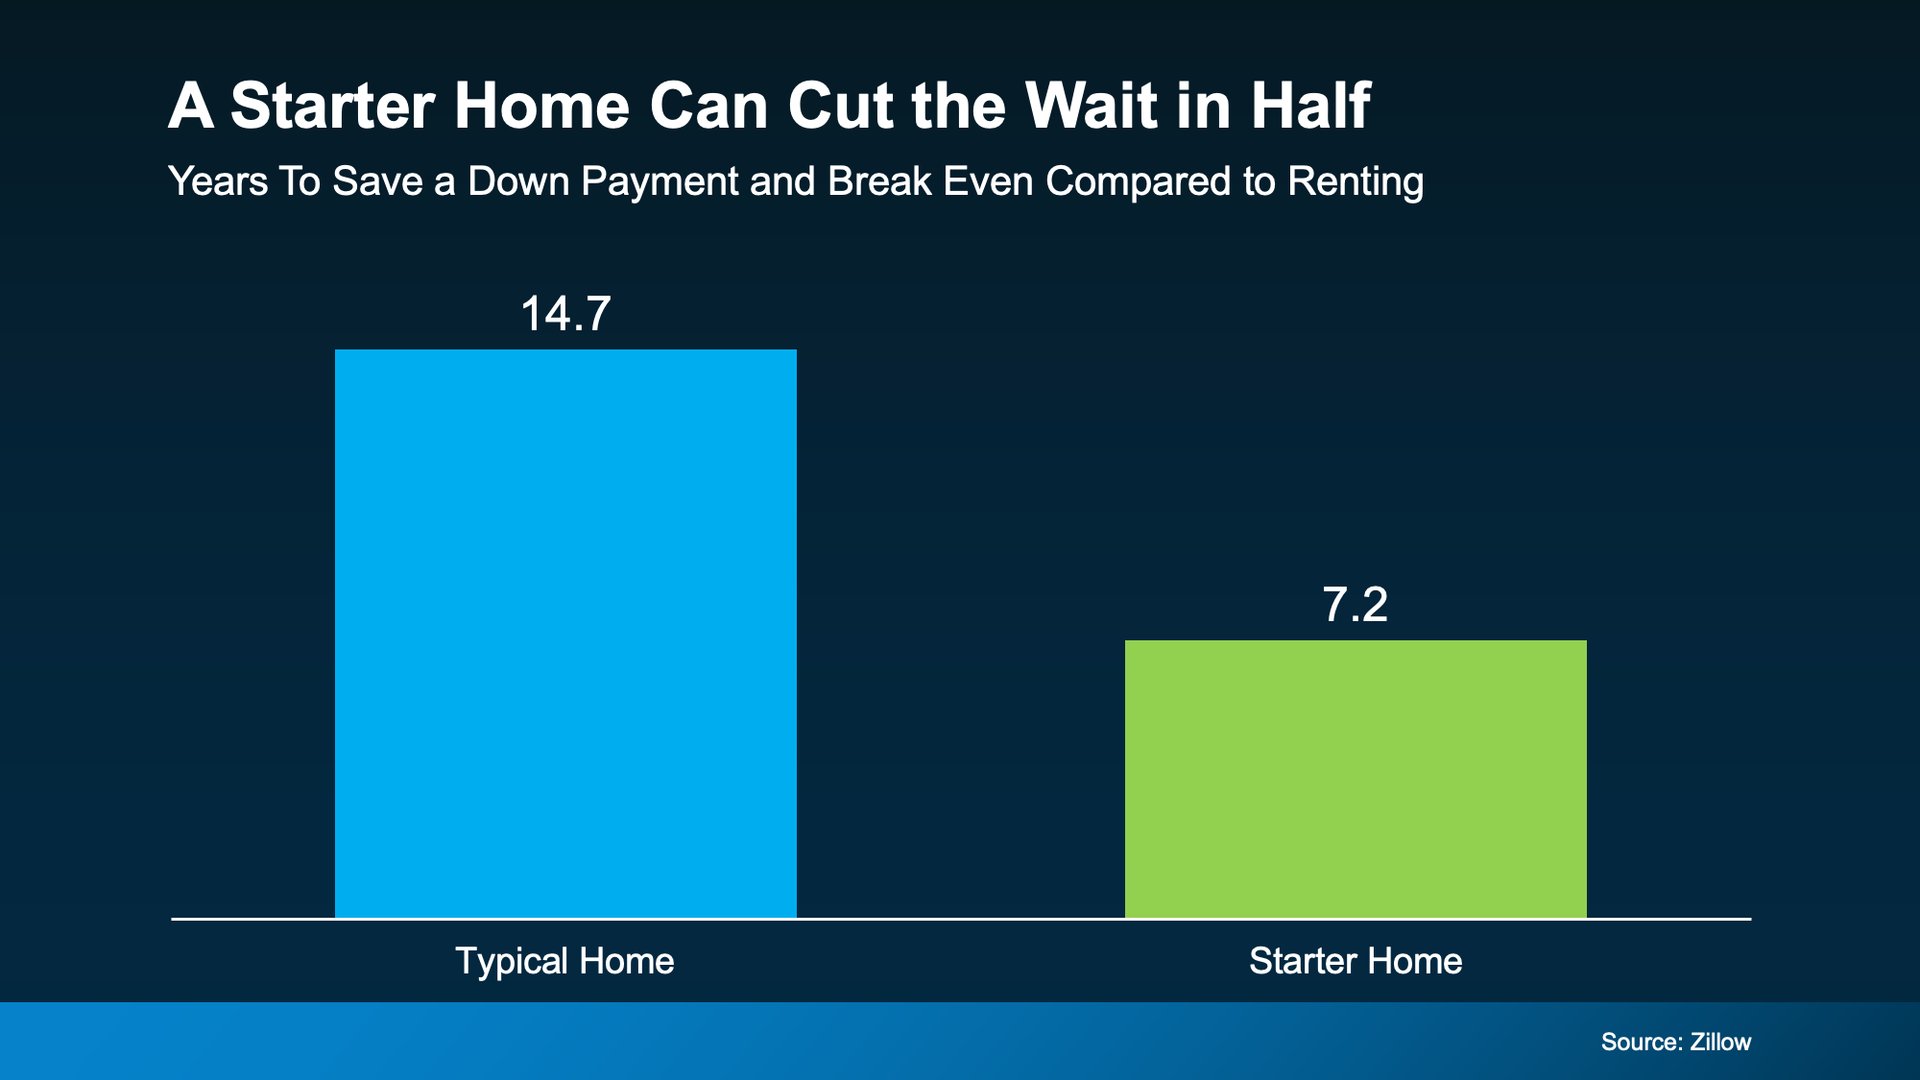
The study estimates 4.6 years to save for a starter home's down payment, followed by 2.6 years after purchasing to reach the financial break-even point.
Those are national estimates, not Tallahassee projections. The actual timeline depends on local home prices, rental costs, financing, maintenance, and how long you stay in the home.
Still, the principle applies here: A lower purchase price can make homeownership possible sooner.
A starter home doesn't have to mean a tiny house or a major renovation project.
It might be a smaller single-family home, an older property that's been well-maintained, or a townhome. What matters most is finding something that meets your needs without stretching your budget.
According to Redfin's August 2026 housing data, the median sale price across home types in Tallahassee was approximately $300,000.
But not every home in Tallahassee costs $300,000.
For example, Realtor.com's September 2026 market data showed median listing prices of approximately $219,900 in ZIP code 32301 and $249,900 in ZIP code 32303. That's noticeably below the citywide median listing price of approximately $332,000.
Of course, listing prices aren't sale prices, and homes vary considerably in size, condition, and features. But those differences illustrate why expanding your search criteria can reveal more affordable options.
The goal isn't necessarily to buy the cheapest home. It's to find a home you can comfortably afford that works for your life today.
And remember, your first home doesn't have to be your forever home.
Here's another misconception that keeps some renters from even considering homeownership.
Many people assume a 20% down payment is required to purchase a house.
It isn't.
According to the National Association of REALTORS®' 2025 Profile of Home Buyers and Sellers, the median down payment for first-time homebuyers nationwide was 10%, compared with 19% for all homebuyers.
And some mortgage programs allow even less.
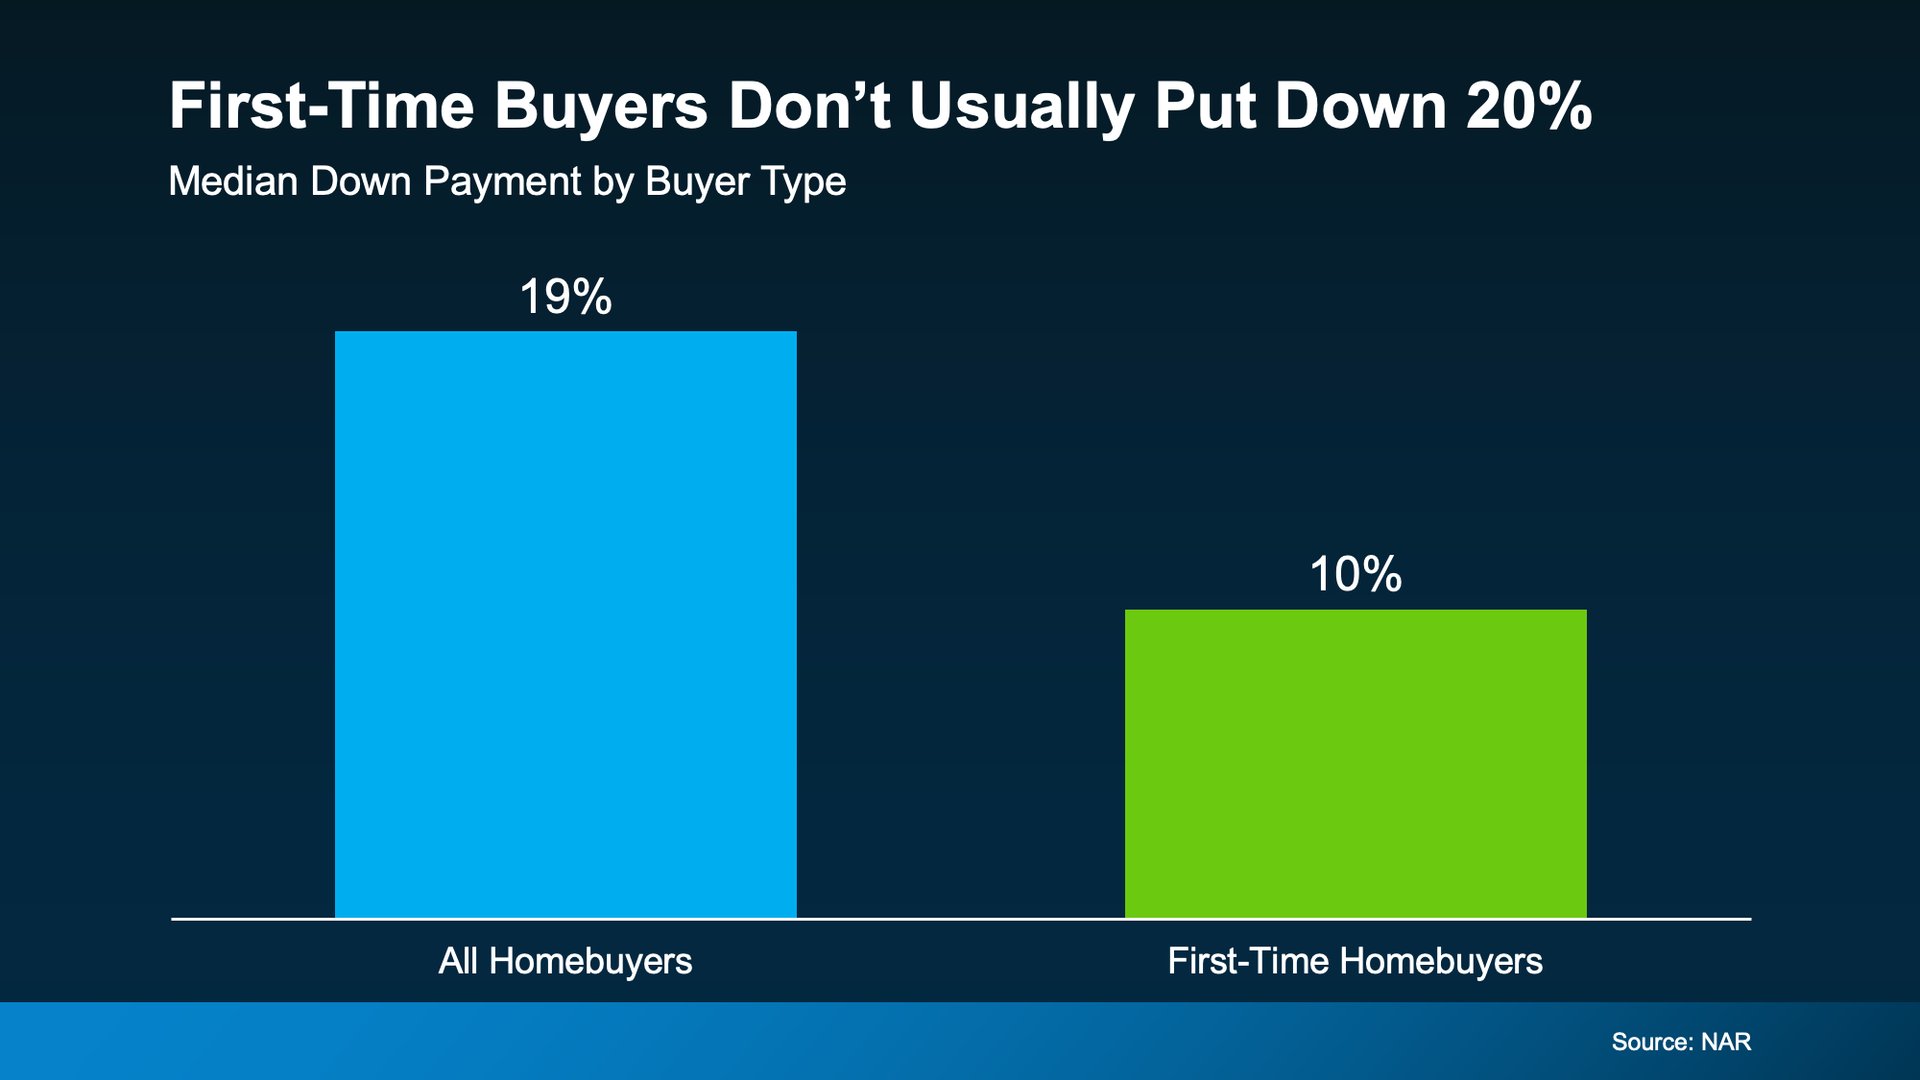
Eligible borrowers may qualify for conventional financing with as little as 3% down or FHA financing with 3.5% down. Certain VA and USDA loans may offer zero-down-payment options.
So what would those percentages actually look like on homes at different Tallahassee price points?
Down Payment | $300,000 Home | $225,000 Home |
|---|---|---|
20% | $60,000 | $45,000 |
10% | $30,000 | $22,500 |
3.5% | $10,500 | $7,875 |
3% | $9,000 | $6,750 |
These are illustrative purchase prices, not a calculation of Tallahassee's official starter-home price threshold. The amounts reflect down payments only, before closing costs and other purchase expenses.
Think about that difference.
Someone waiting to save $60,000 for a 20% down payment on a $300,000 home might discover that a $225,000 property could require just $7,875 down with an eligible 3.5% down loan.
That doesn't mean financing $225,000 with 3.5% down is automatically the better financial decision. Smaller down payments generally mean borrowing more money, potentially higher monthly payments, and mortgage insurance.
But it does mean the amount you need saved before purchasing could be considerably lower than expected.
Here's where the local picture gets even more interesting.
There are programs specifically designed to help eligible Tallahassee and Leon County homebuyers with down payments and closing costs.
And some people who could qualify may not realize these resources exist.
City of Tallahassee Down Payment Assistance
The City of Tallahassee offers assistance administered by the Tallahassee Lenders' Consortium.
Eligible homebuyers may qualify for assistance of up to 20% of the purchase price, subject to income, property, and program requirements.
The Consortium's published guidelines include a maximum existing-home purchase price of $254,000 and a maximum new-construction purchase price of $304,000, effective December 1, 2025.
The assistance is structured as a deferred, zero-interest loan that may be forgiven after 15 years, provided the program's requirements are met. Certain events, including selling or refinancing before forgiveness, can trigger repayment.
Leon County Down Payment Assistance
Leon County also offers assistance through the State Housing Initiatives Partnership (SHIP) program.
According to the Tallahassee Lenders' Consortium, eligible households may receive assistance ranging from $7,500 to $25,000, depending on income qualifications and the type of property being purchased.
The County's program generally requires approved homebuyer education, qualifying mortgage financing, and at least $500 of the homebuyer's own funds.
Florida Housing Assistance Programs
The Florida Housing Finance Corporation also offers mortgage and down payment assistance programs through participating lenders.
One example is Florida Assist, which provides up to $10,000 in assistance through an interest-free, deferred second mortgage for eligible borrowers.
Florida's Hometown Heroes program may also provide assistance for qualifying workers in designated occupations, including certain healthcare, education, childcare, public safety, and military roles.
These programs have eligibility requirements, and funding availability can change. Some assistance is forgivable, while other assistance must eventually be repaid. Not every program can be combined with every mortgage.
The important thing is to explore these options before assuming you don't have enough saved.
While a smaller down payment can make purchasing easier, saving less upfront doesn't necessarily make owning less expensive.
Your actual monthly housing expense matters just as much.
Beyond principal and interest, homeowners need to account for property taxes, homeowners insurance, possible mortgage insurance, and any applicable HOA or condominium fees.
There are also inspection costs, closing expenses, moving costs, and maintenance to consider.
And with an older or more affordable home, paying attention to the roof, HVAC system, plumbing, and other major components is particularly important. A lower purchase price doesn't always translate into a lower total cost of ownership.
That's why comparing renting versus buying should involve more than looking at your current rent and a potential mortgage payment.
It should also account for how long you expect to remain in the property, your savings, your financial flexibility, and the responsibilities that come with ownership.
If you've been putting off buying your first home in Tallahassee because you think you need 20% down, it may be worth revisiting that assumption.
A more affordable starter home, a lower down payment, and qualifying assistance programs can significantly change how much money you need upfront.
That doesn't mean everyone should rush into buying. Sometimes renting longer is the better financial choice.
But you shouldn't have to guess whether homeownership is possible.
Find out when the next Tallahassee Homebuyer Class and Workshop is to help you understand the process, explore financing options, learn about local assistance programs, and make informed decisions about your next steps.
And when you're ready to start exploring, you can sign up for customized Tallahassee listing alerts to see homes that fit your budget, including Coming Soon properties which typically don't feed over to the popular third-party search websites.
Your first home might be closer than you think. The first step is understanding your options.
Stay up to date on the latest real estate trends.
All Real Estate News
November 10, 2026
All Real Estate News
November 10, 2026
Local Events
November 7, 2026
Local Events
November 6, 2026
All Real Estate News
November 4, 2026
All Real Estate News
November 3, 2026
You’ve got questions and we can’t wait to answer them.