There Isn’t Just One Tallahassee Housing Market Right Now
September 30, 2026
All Real Estate News
September 30, 2026
All Real Estate News
If the housing market feels confusing right now, part of the problem may be that we keep talking about it as though everyone is experiencing the same market.
They aren't.
A seller with a 3% mortgage is making a very different decision than someone who owns a home outright. A financed buyer watching mortgage rates is operating under different constraints than a cash buyer. And a homebuilder with completed inventory may have very different motivations than an individual homeowner putting a house on the market.
That is why one national description of today's housing market has been getting attention.
Ryan Serhant, CEO of SERHANT, recently put it this way:
“There is no longer a housing market . . . There are four Americas.”
That may be a little dramatic, but the underlying idea makes sense.
And it applies surprisingly well to Tallahassee.
Here are four groups operating in today's market, and why understanding which one you are dealing with can change the way you approach a move.
Cash remains a major force in real estate.
Nationally, 31.4% of home purchases during the first four months of 2026 were cash purchases, according to Realtor.com. In Florida, the share was even higher at 41.3%.
But that statewide figure should not automatically be applied to Tallahassee. Florida includes retirement, vacation-home, luxury, and second-home markets where cash purchases can be especially common.
What may be even more useful is looking at where cash purchases occur.
Realtor.com's data show a striking U-shaped pattern.
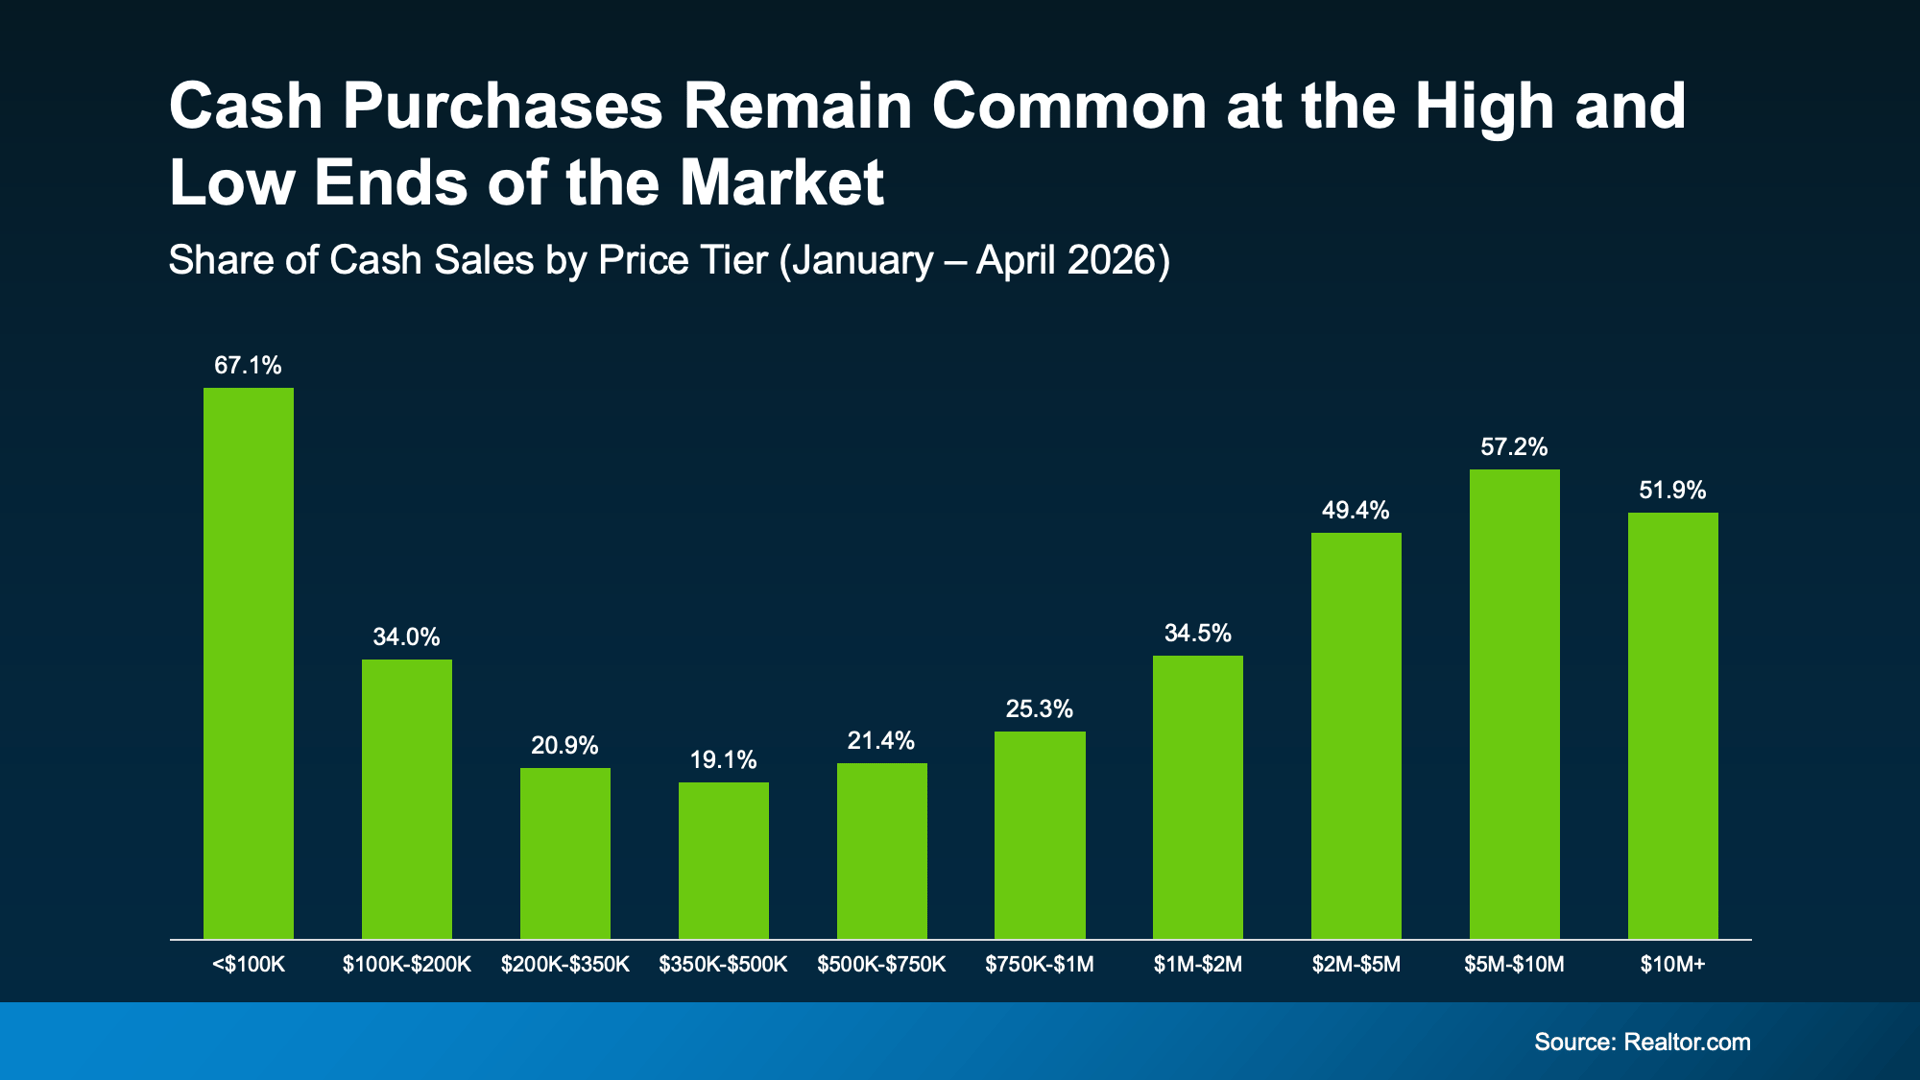
From January through April 2026:
• 67.1% of purchases below $100,000 were cash
• 34.0% between $100,000 and $200,000 were cash
• 20.9% between $200,000 and $350,000 were cash
• 19.1% between $350,000 and $500,000 were cash
• 21.4% between $500,000 and $750,000 were cash
• Cash activity then climbed sharply again in the luxury market
That matters in Tallahassee because our market has meaningful activity at both ends.
A lower-priced property that needs work, a vacant lot, or an investment property may attract a very different buyer pool than a move-in-ready home in the middle of the market.
At the opposite end, higher-net-worth purchasers may be less affected by mortgage rates altogether.
For sellers, that means the strongest offer is not always simply the highest number.
A cash offer may eliminate a financing contingency, reduce certain appraisal concerns, and potentially offer a faster closing. But that certainty can sometimes come with a lower purchase price.
The whole offer matters.
For buyers using cash, the advantage is real, but cash does not automatically mean a seller will accept a substantially lower price. Property condition, competing offers, timing, and the seller's priorities still matter.
Most people buying homes are still using financing, and this group has been dealing with one of the biggest challenges of the 2026 housing market: mortgage rates.
The outlook has also changed as the year has progressed.
A Fannie Mae survey of housing experts found that 48% had raised their long-term mortgage-rate outlook based on developments during 2026, while only 3% had lowered it.
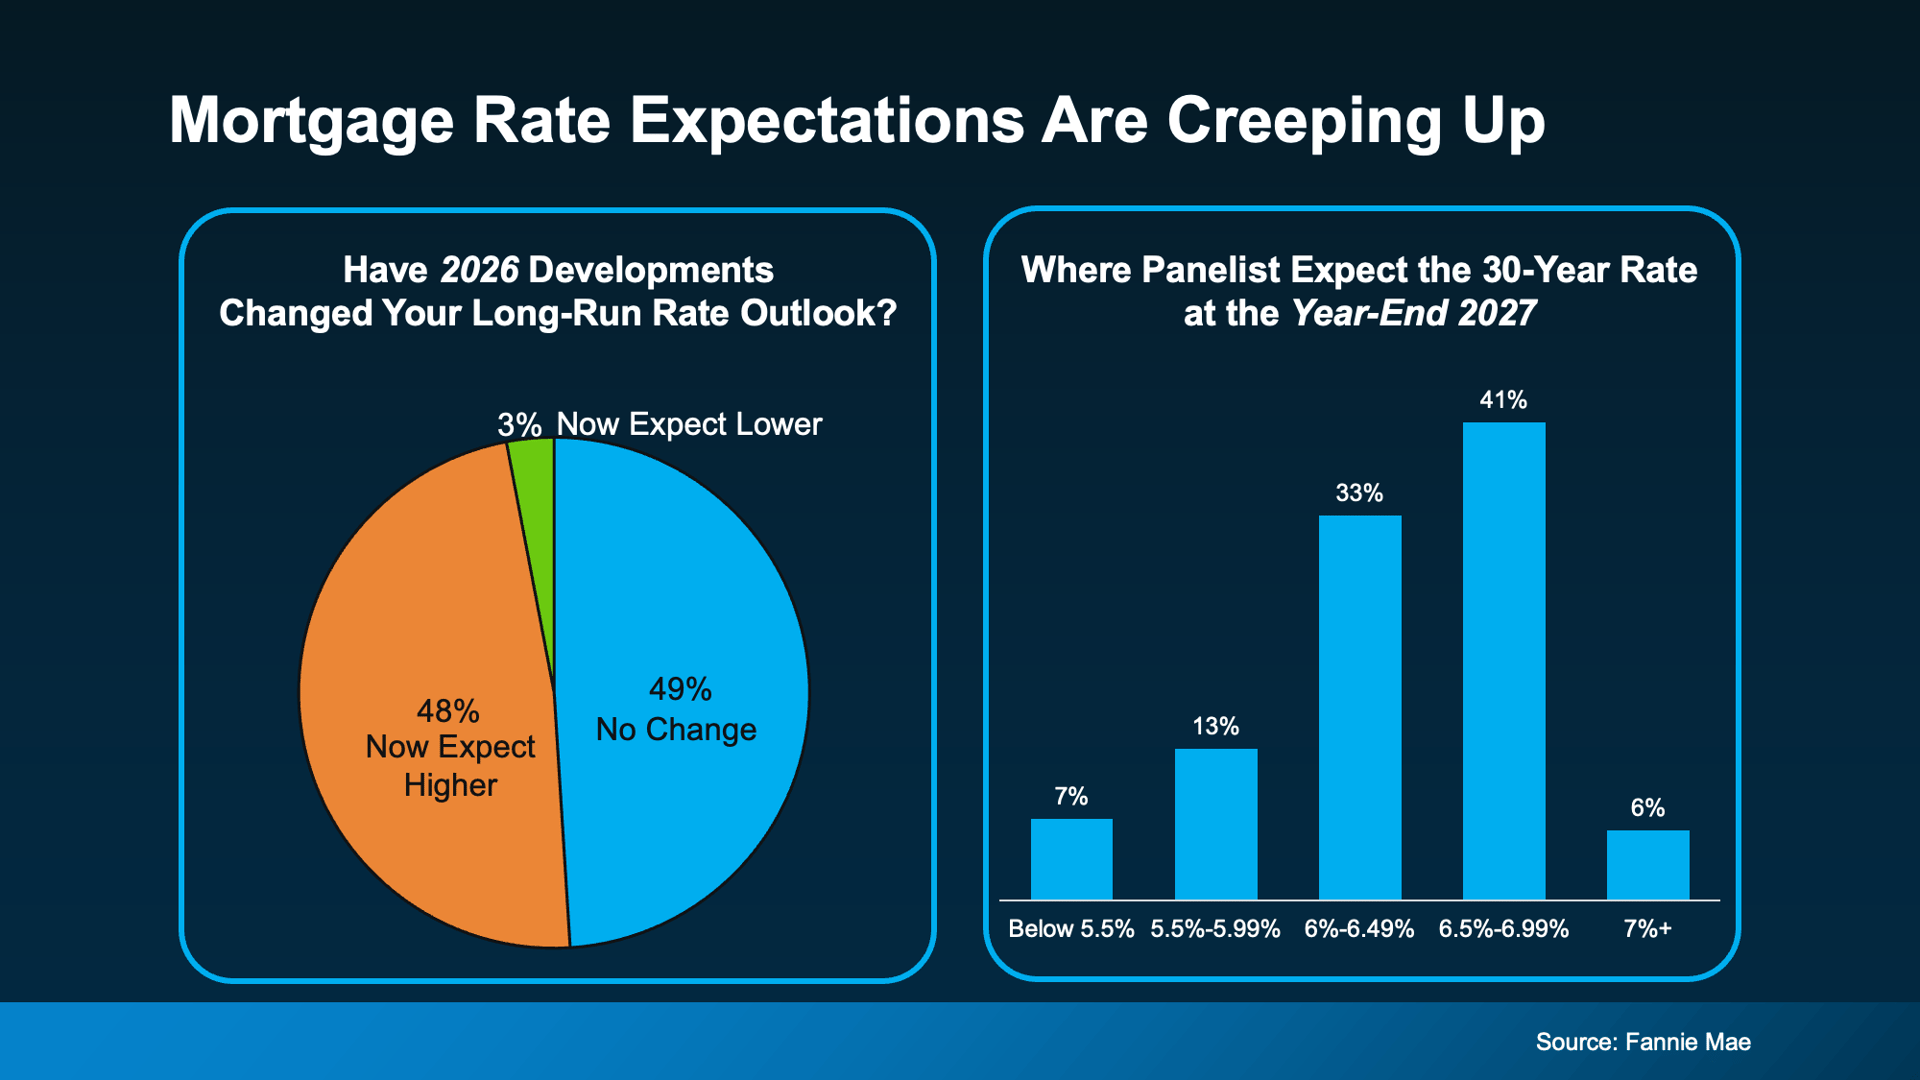
When asked where they expected the 30-year mortgage rate to be at the end of 2027:
• 7% expected a rate below 5.5%
• 13% expected 5.5% to 5.99%
• 33% expected 6.0% to 6.49%
• 41% expected 6.5% to 6.99%
• 6% expected 7% or higher
That does not mean mortgage rates will follow that exact path.
Forecasts change because inflation, economic growth, employment data, geopolitical events, oil prices, Federal Reserve policy, and bond-market expectations change too.
But it does illustrate the danger of building an entire homebuying plan around the assumption that significantly lower rates are right around the corner.
Tallahassee buyers do have something they did not have several years ago: more room to negotiate.
In August 2026, Tallahassee had 1,786 active residential listings, 308 price reductions, and a 97.59% sale-to-list price ratio, according to the Tallahassee Board of REALTORS® and Altos Research data we've been tracking.
Redfin's August numbers tell a similar story, with Tallahassee homes selling for about 97.9% of asking price.
That does not mean every seller will provide a concession.
But it does mean today's financed buyer may be able to look beyond just the asking price.
Depending on the property and transaction, negotiations may involve:
• Purchase price
• Closing-cost assistance
• Repairs
• Rate-buydown contributions
• Home warranties
• Closing date
• Other contract terms
Instead of making an entire buying decision depend on where mortgage rates may go next, it can be more useful to ask whether the property, financing, and negotiated terms can make today's numbers work.
Then there are homeowners who already have mortgages.
For many of them, moving is not simply a question of whether they like another house better.
It means giving up an interest rate they may never see again.
According to Federal Housing Finance Agency data, 66.7% of outstanding mortgages in the first quarter of 2026 carried an interest rate below 5%.
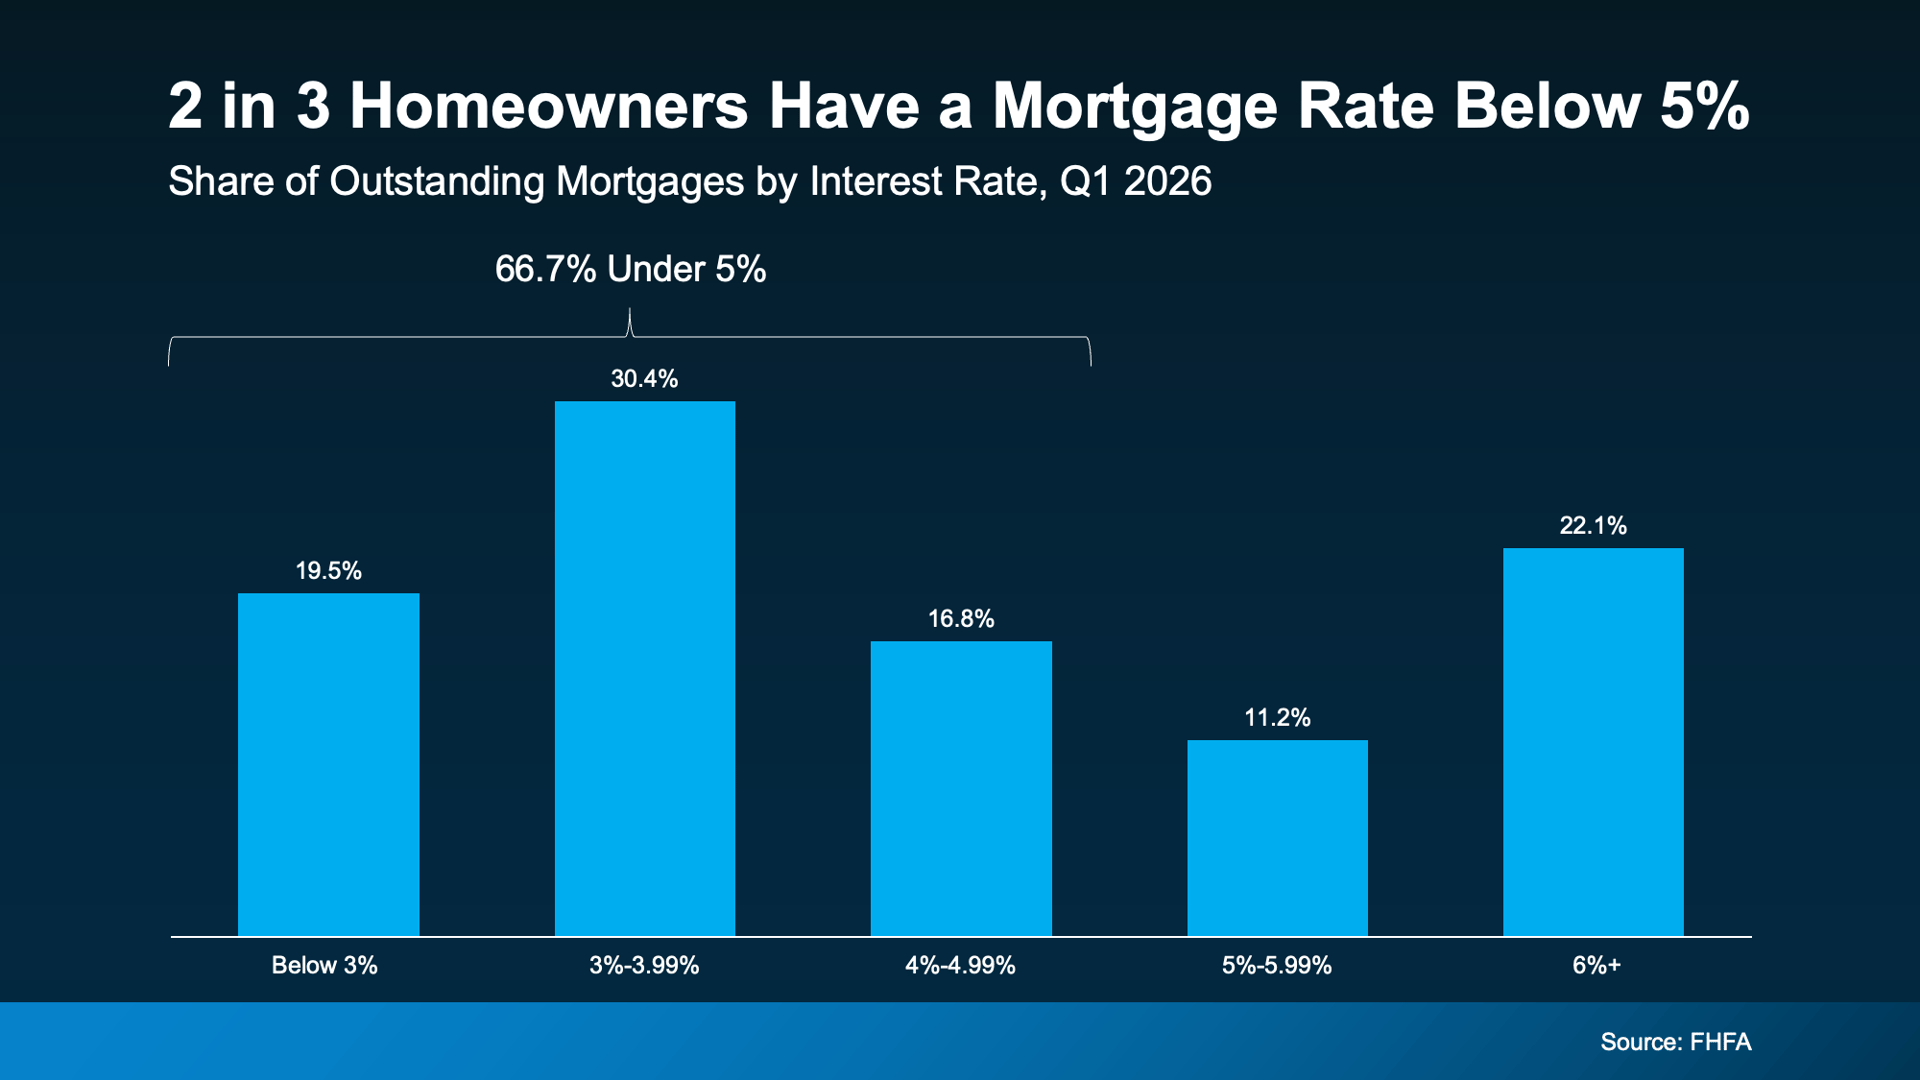
Breaking that down further:
• 19.5% were below 3%
• 30.4% were between 3% and 3.99%
• 16.8% were between 4% and 4.99%
FHFA's National Mortgage Database confirms that its latest outstanding-mortgage statistics extend through Q1 2026.
That is an enormous number of homeowners with financing well below today's prevailing mortgage rates.
And it helps explain why some owners who would otherwise consider moving are staying put.
The important word is some.
People still move because jobs change, families grow, relationships change, children leave home, health needs change, people inherit property, and life happens.
A low mortgage rate can influence the decision, but it does not eliminate the reasons people move.
For Tallahassee sellers considering a move, the better question may not be:
"Why would I ever give up my rate?"
It may be:
"What would the entire move look like financially?"
Homeowners who have owned their properties for several years may also have substantial equity. That equity can change the down payment, loan amount, monthly payment, and overall affordability of the next purchase.
Some government-backed mortgages may also be assumable under certain circumstances, which can potentially create an additional selling feature. Buyers and sellers considering that option should work directly with the loan servicer and appropriate professionals to understand eligibility and requirements.
New construction creates another layer.
Builders are not making the same decisions an individual homeowner makes.
They may have completed inventory, construction loans, carrying costs, quarterly sales goals, upcoming phases, and additional lots they need to sell.
That can create incentives.
Nationally, new-home inventory has been elevated, and builders have increasingly used mortgage-rate incentives, closing-cost assistance, upgrades, and price adjustments to attract buyers.
Tallahassee has enough new construction for this to matter locally too.
During August, we were tracking roughly 100 active newly built homes in the Tallahassee market, with an average asking price around $400,000.
That means sellers of existing homes are sometimes competing not only with the house down the street, but also with a builder offering a brand-new home and a financing incentive.
That does not automatically make new construction the better deal.
It means the comparison has to go deeper than asking price.
A buyer comparing an existing $375,000 home with a $400,000 new construction home may discover that a builder's financing incentive narrows the monthly-payment difference considerably.
Or, after comparing taxes, HOA costs, lot size, upgrades, location, landscaping, lender fees, and the full financing package, the existing home may offer better overall value.
You have to run the numbers.
For sellers of existing homes, competing with new construction also does not mean trying to turn a resale home into a new one.
Existing homes can offer advantages builders often cannot recreate immediately, including:
• Established neighborhoods
• Mature landscaping
• Larger lots
• Finished window treatments
• Fences, sheds, and outdoor improvements
• Existing neighborhood amenities
• Immediate availability
• Upgrades already completed by previous owners
The goal is to understand what the competing buyer sees and position the property accordingly.
There is one more wrinkle locally.
Even inside these four groups, Tallahassee does not behave like one single housing market.
A $175,000 home, a $325,000 home, a $650,000 home, and a $1.2 million home can have very different inventory, competition, financing, days on market, and buyer pools.
Our August market had 1,786 active listings and a median sale price of $300,000, but those citywide numbers are averages across many very different types of real estate.
That is why headlines such as "sellers still have leverage" or "buyers have the advantage" can both be true at the same time.
The answer may depend on the price point, neighborhood, property type, condition, financing, and competition surrounding one particular home.
For sellers, the important questions include:
For buyers, the questions are different:
Those answers can be much more useful than trying to determine whether the overall Tallahassee market is simply "good" or "bad."
There may be one Tallahassee housing market on paper, but sellers, cash buyers, financed buyers, rate-locked homeowners, and builders are not experiencing it the same way.
Cash changes an offer.
Financing changes affordability.
A low existing mortgage rate changes the decision to sell.
Builder incentives change the competition.
And price point can change almost everything.
That is why today's real estate market requires more than a national headline or a citywide average.
The better question is not:
"How is the Tallahassee housing market?"
It is:
"How is the Tallahassee housing market for this property, at this price, for this seller or buyer, right now?"
Stay up to date on the latest real estate trends.
All Real Estate News
September 30, 2026
All Real Estate News
September 29, 2026
All Real Estate News
September 28, 2026
All Real Estate News
September 27, 2026
All Real Estate News
September 26, 2026
All Real Estate News
September 25, 2026
You’ve got questions and we can’t wait to answer them.