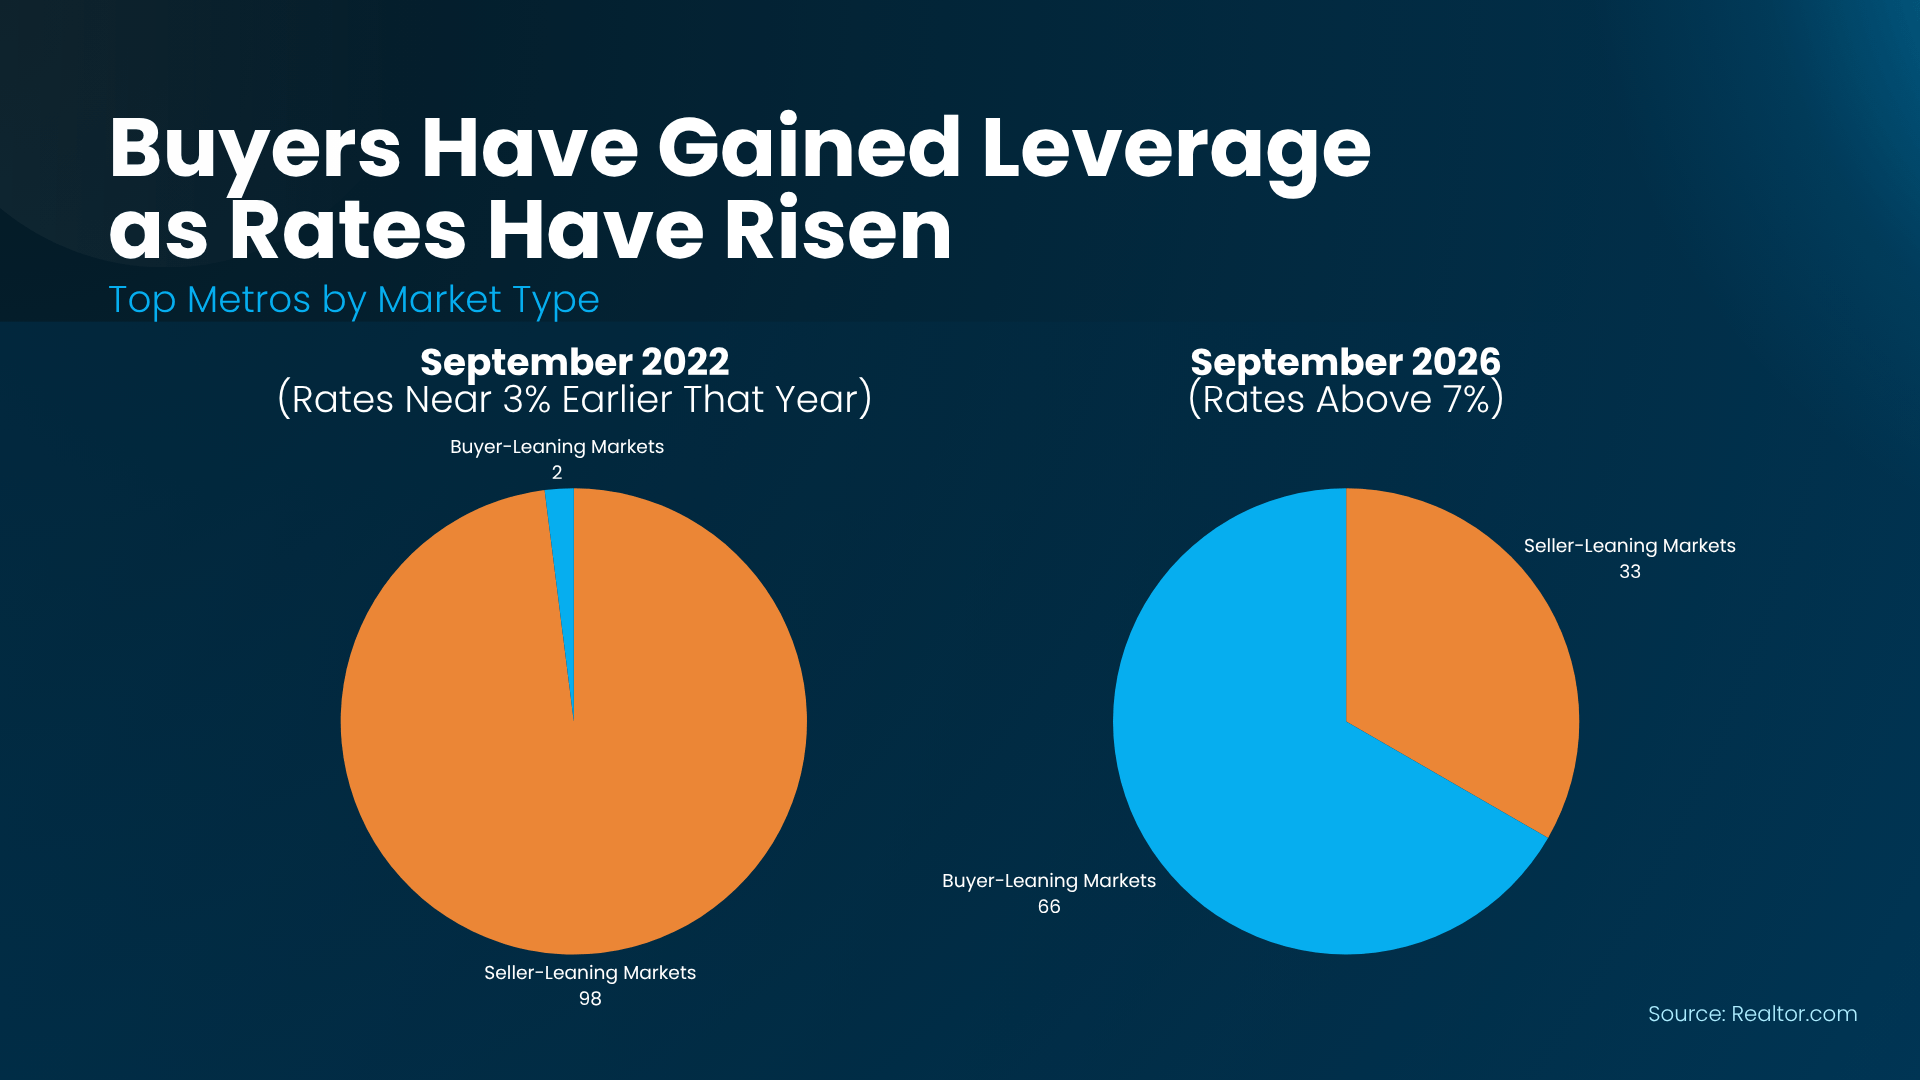Waiting for Lower Mortgage Rates? Here's the Trade-Off.
November 17, 2026
All Real Estate News
November 17, 2026
All Real Estate News
If you've been watching mortgage rates lately, you might feel like buying a home has become a waiting game.
Rates climbed above 7% this fall, making monthly payments more expensive and leaving plenty of prospective homebuyers wondering whether they should put their plans on hold until borrowing costs come down.
And that sounds reasonable. After all, who wouldn't want a lower mortgage payment?
But here's something worth considering: When mortgage rates are low, competition for homes can be high. And when rates are higher, you may have more room to negotiate.
That trade-off could be particularly important for anyone looking to purchase a home right now.
Because while mortgage rates affect what you can afford, they're not the only thing that determines whether you're getting a good deal.
Remember the housing market in 2020 and 2021?
Mortgage rates were hovering around 3%, and homebuyers were eager to take advantage of historically low borrowing costs.
But those low rates created a problem. With so many people looking for homes and relatively few properties available, competition became intense.
Homes received multiple offers, properties sold above asking price, and some buyers even agreed to waive inspection contingencies or other protections to make their offers more competitive.
Sellers had considerable negotiating power because they often had multiple interested buyers to choose from.
As rates climbed in 2022, affordability became more challenging, reducing demand and gradually shifting market conditions.
According to Realtor.com's October 2026 Market Clock report, 98 of the nation's 100 largest metropolitan markets favored sellers at the height of the market in spring 2022.
By October 2026, approximately two-thirds of those markets either favored buyers or were moving in that direction.
That doesn't mean every market has suddenly become a buyer's market. In fact, only 17 of those 100 metros were classified as outright buyer's markets, while another 49 were balanced but moving in a more buyer-friendly direction.
And that distinction is particularly important here in Tallahassee.
Not exactly. But the numbers suggest there may be opportunities for buyers who understand where to look.
According to Tallahassee-area single-family market data from September 2026, there were 3.8 months of housing inventory, unchanged from the previous year.
That doesn't indicate an overwhelming surplus of homes, but it also doesn't mean sellers have unlimited negotiating power.
And another statistic is worth examining.
In September 2026, Tallahassee-area sellers received a median of 97% of their original asking price, compared with 97.7% one year earlier.
Meanwhile, the median sale price declined 5.7% year over year, from $349,950 to $329,950.
Those figures suggest that sellers aren't necessarily achieving the prices they originally hoped for.
However, the market isn't slowing across every measure.
The median time to contract actually improved from 54 days in September 2025 to just 32 days in September 2026.
So, what does that mean for someone hoping to buy a home in Tallahassee?
It means negotiating opportunities may depend heavily on the individual property.
A well-priced home in good condition may still attract interest relatively quickly. Meanwhile, a property that's been sitting on the market, recently reduced its asking price, or needs repairs may present more opportunities to negotiate.
And that's where having an experienced local real estate agent can make a difference.
Instead of assuming every listing has the same negotiating potential, your agent can help evaluate comparable sales, recent price adjustments, competing listings, and the property's history.
Because sometimes the best opportunity isn't the home with the biggest price reduction. It's the one where the seller is willing to negotiate terms that make the purchase more affordable for you.
Here's where today's market conditions could work in your favor.
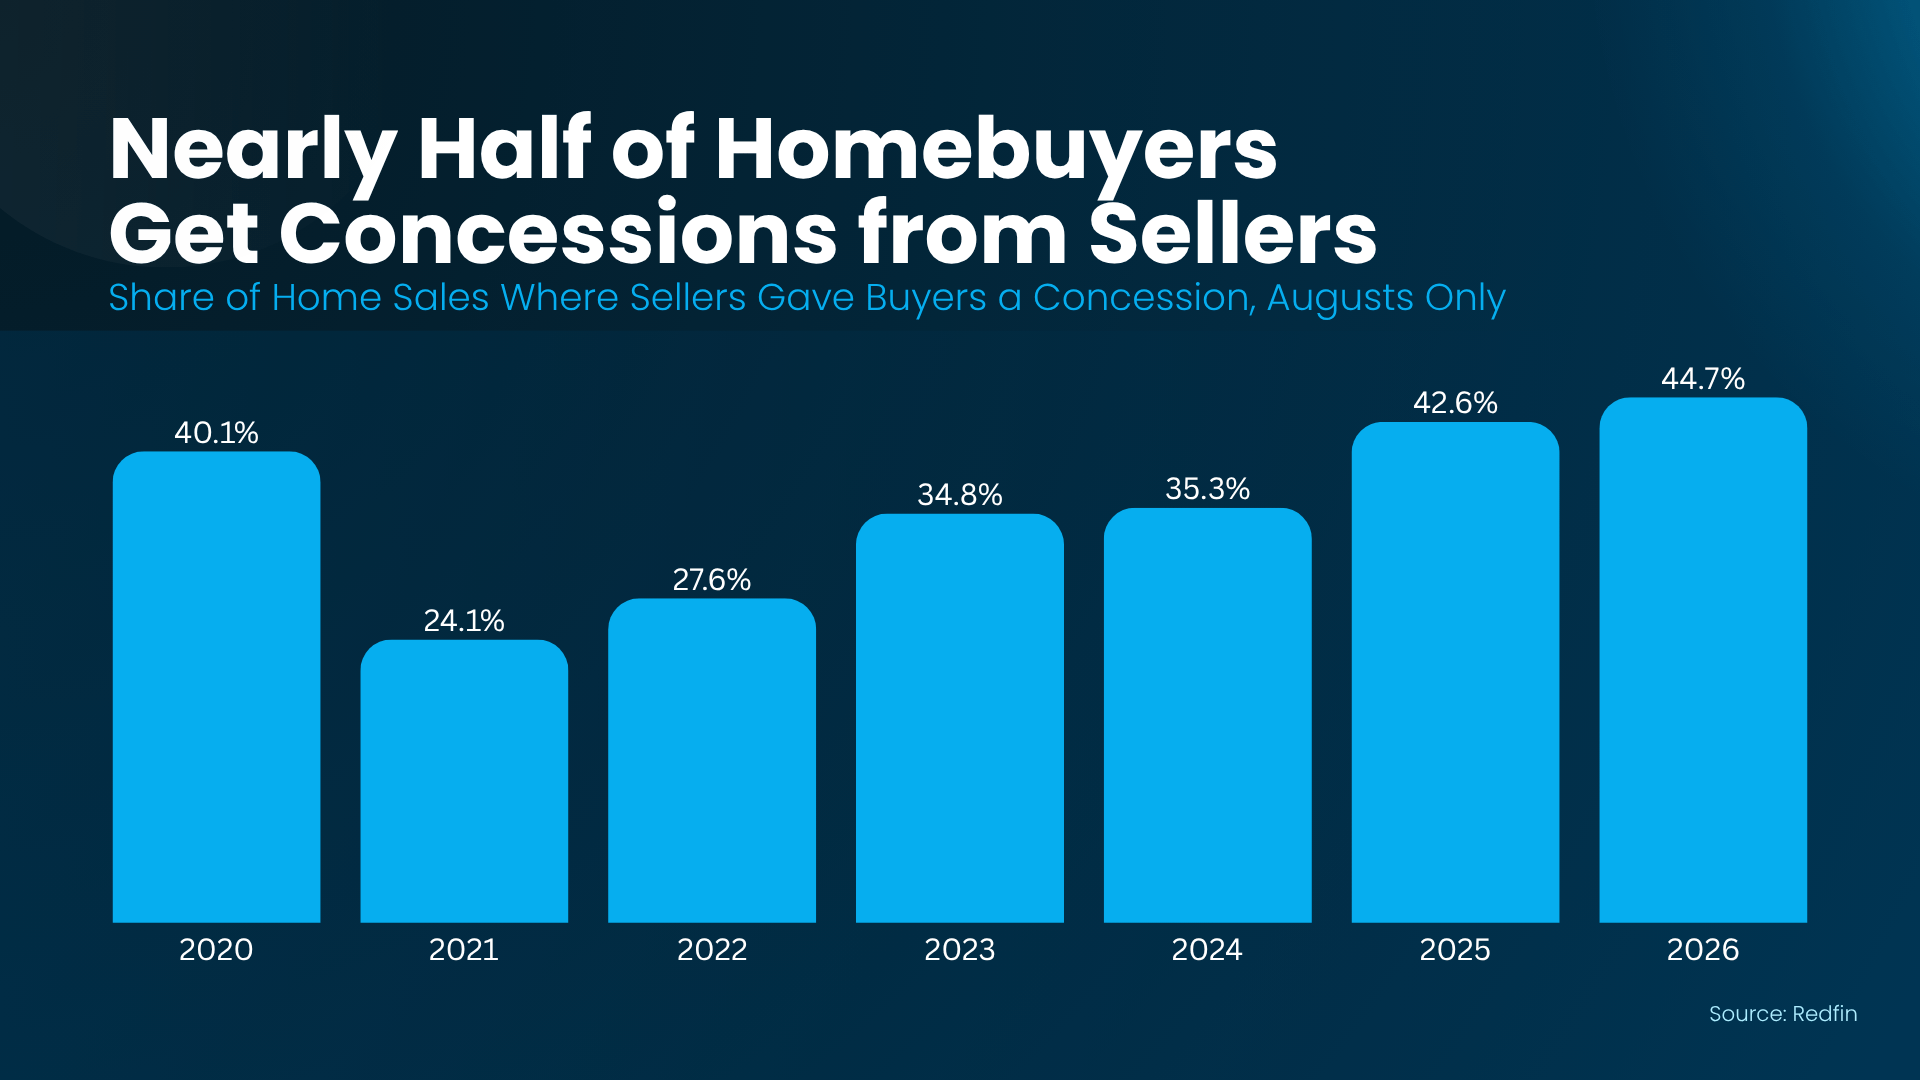
According to Redfin, sellers provided concessions in 44.7% of U.S. home sales during the three months ending in August 2026.
That's up from 42.6% during the same period a year earlier.
A seller concession is an agreed contribution or benefit that helps make a transaction work. It could involve assistance with certain closing costs, repairs, or mortgage financing expenses.
And for Tallahassee homebuyers, there are several ways those negotiations might help.
Your down payment isn't the only money you need when purchasing a home.
There are also lender fees, title-related expenses, insurance costs, prepaid expenses, and other closing costs.
Depending on the financing program, a seller may agree to contribute toward eligible closing costs.
That could mean keeping more of your savings available for moving expenses, improvements, or unexpected costs after closing.
Keep in mind that seller contributions are subject to loan program limitations, and they generally cannot be used to satisfy your required down payment.
Another option is negotiating for the seller to contribute toward a mortgage rate buydown.
A permanent buydown generally involves paying discount points to obtain a lower interest rate for the life of the loan. A temporary buydown reduces the borrower's payment for a specified initial period before it increases to the full contractual payment.
Both options have costs, restrictions, and trade-offs that should be reviewed with a qualified lender.
Depending on the numbers, a seller-paid buydown may provide greater monthly payment benefits than negotiating an equivalent reduction in the asking price.
But the details matter. A temporary buydown doesn't eliminate the higher payment that follows, and neither type guarantees that you'll be able to refinance later.
Not every home is going to be move-in ready.
Tallahassee has a wide variety of properties, from newer construction to older homes that may need roof, plumbing, electrical, or other improvements.
Depending on the property, inspection results, and contract terms, buyers may be able to negotiate for repairs, a price adjustment, or an allowable closing credit.
But there's an important distinction between negotiating a discount and negotiating a good deal.
A property listed below comparable sales may already be competitively priced, even if the seller won't make additional concessions.
The goal is to understand the property's value, condition, and total ownership costs before deciding what to offer.
This is the question a lot of Tallahassee homebuyers are asking.
And the latest mortgage forecasts suggest that waiting may not necessarily produce the dramatic savings some are expecting.
According to Freddie Mac, the average 30-year fixed mortgage rate was 7.11% as of November 12, 2026.
That's down from 7.40% in mid-October, but still substantially higher than the rates available during 2020 and 2021.
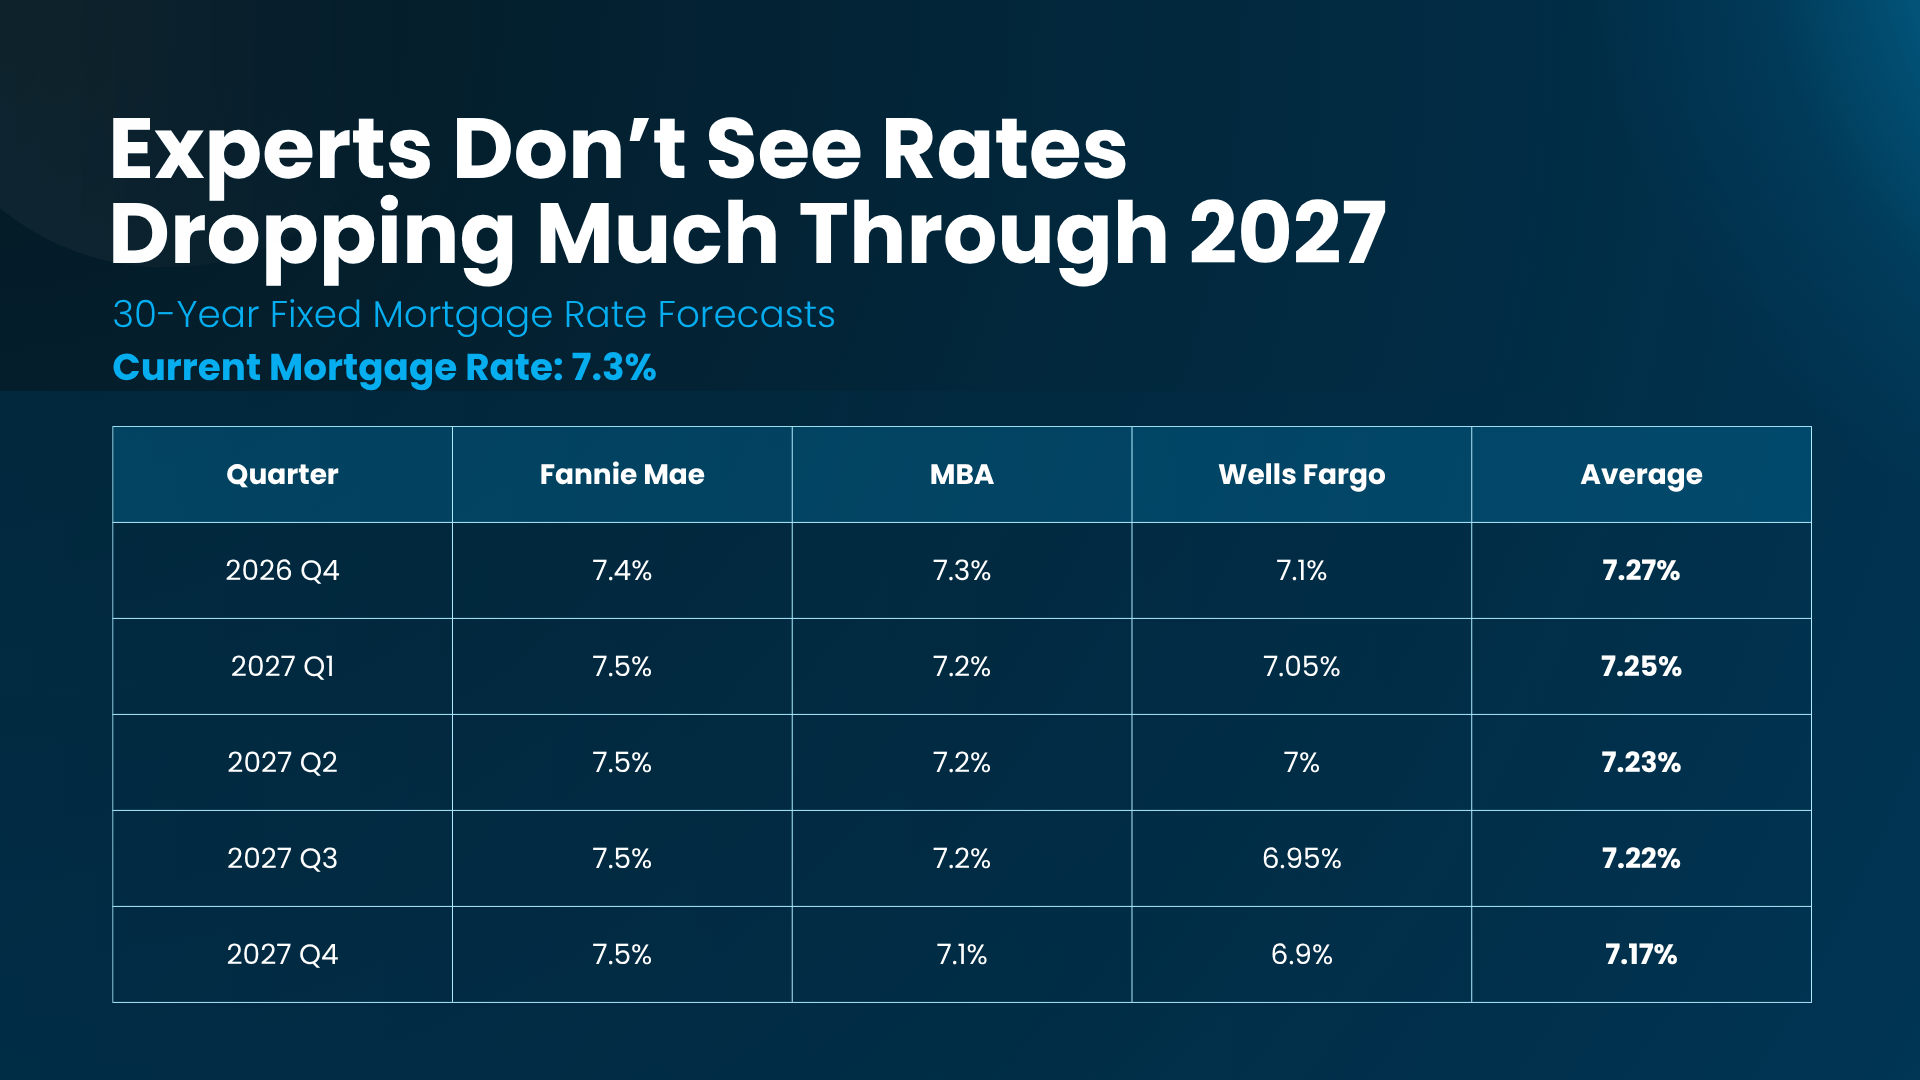
Meanwhile, October 2026 forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo suggest mortgage rates may remain relatively elevated through 2027.
Their projections for the fourth quarter of 2027 range from approximately 6.9% to 7.5%.
Of course, these are forecasts, not guarantees. Economic conditions, inflation, Federal Reserve policy, and bond market movements could push rates higher or lower than expected.
But here's the trade-off.
If mortgage rates decline significantly, more potential buyers may decide to enter the market.
That could mean greater competition for desirable homes and less willingness from sellers to negotiate.
Alternatively, rates could remain elevated, leaving those who waited with similar borrowing costs and potentially different home prices or inventory conditions.
Waiting for a lower mortgage rate isn't necessarily a bad decision. But waiting doesn't guarantee a better buying opportunity, either.
Let's say you find a home that meets your needs, fits comfortably within your budget, and is priced appropriately for its condition.
Maybe the seller is willing to contribute toward closing costs. Or perhaps the property has been on the market long enough that there's an opportunity to negotiate the asking price.
Those benefits could make purchasing today more attractive than simply waiting for mortgage rates to decline.
On the other hand, if the monthly payment stretches your budget too far, potential concessions shouldn't be used to justify taking on more debt than you can comfortably afford.
And buying a home with the expectation that you'll refinance soon is never a guarantee. Future rates, property values, your financial circumstances, and refinancing costs will all play a role.
Ultimately, a good home purchase is about more than getting the lowest possible interest rate.
It's about finding a property that meets your needs, negotiating favorable terms when possible, and making sure the total cost of ownership works for you.
If you're considering purchasing a home, the first step isn't necessarily scheduling a showing.
It's understanding your numbers.
Talk with a qualified mortgage lender about your financing options, current interest rates, and how closing cost assistance or a rate buydown might affect your purchase.
Then work with a local real estate agent who can help identify properties where the asking price, days on market, competing inventory, or seller circumstances may create negotiating opportunities.
See if your area offers a Homebuyer Class or Workshop, where you can learn about financing, the purchase process, and other considerations before making a move.
And remember, not every home is going to offer the same opportunity.
Some sellers may be willing to negotiate significantly. Others may already be priced competitively.
Understanding the difference can help you make a more informed decision.
Mortgage rates may eventually come down, but that doesn't necessarily mean waiting will result in a better overall deal.
While today's borrowing costs remain a challenge, Tallahassee's housing market is also creating opportunities to negotiate prices, closing costs, repairs, and other terms.
The key is understanding which opportunities actually improve your financial position.
Because buying a home isn't just about getting the lowest mortgage rate. It's about getting the right home at a price and payment that make sense for you.
And sometimes, that opportunity is available before mortgage rates reach the number you've been waiting for.
Stay up to date on the latest real estate trends.
All Real Estate News
November 17, 2026
All Real Estate News
November 16, 2026
All Real Estate News
November 15, 2026
All Real Estate News
November 13, 2026
All Real Estate News
November 12, 2026
All Real Estate News
November 11, 2026
You’ve got questions and we can’t wait to answer them.