Will You Regret Buying a Home Now? Here's what the 2026 Data Says.
October 19, 2026
Articles for Buyers
October 19, 2026
Articles for Buyers
Buying a home is a big decision. And with today's mortgage rates, home prices, insurance costs, and general economic uncertainty, it's understandable if you're wondering whether now is really the right time.
After all, nobody wants to buy a home only to watch its value drop a few months later.
But here's something interesting: Most people who have already purchased their current home are glad they did. And when we look at both national trends and what's happening in the housing market, there's some important perspective worth considering.
According to a 2026 NerdWallet survey, 74% of Americans who purchased their current home say they're glad they made that decision. Just 3% say they regret it.
That's a pretty significant difference.
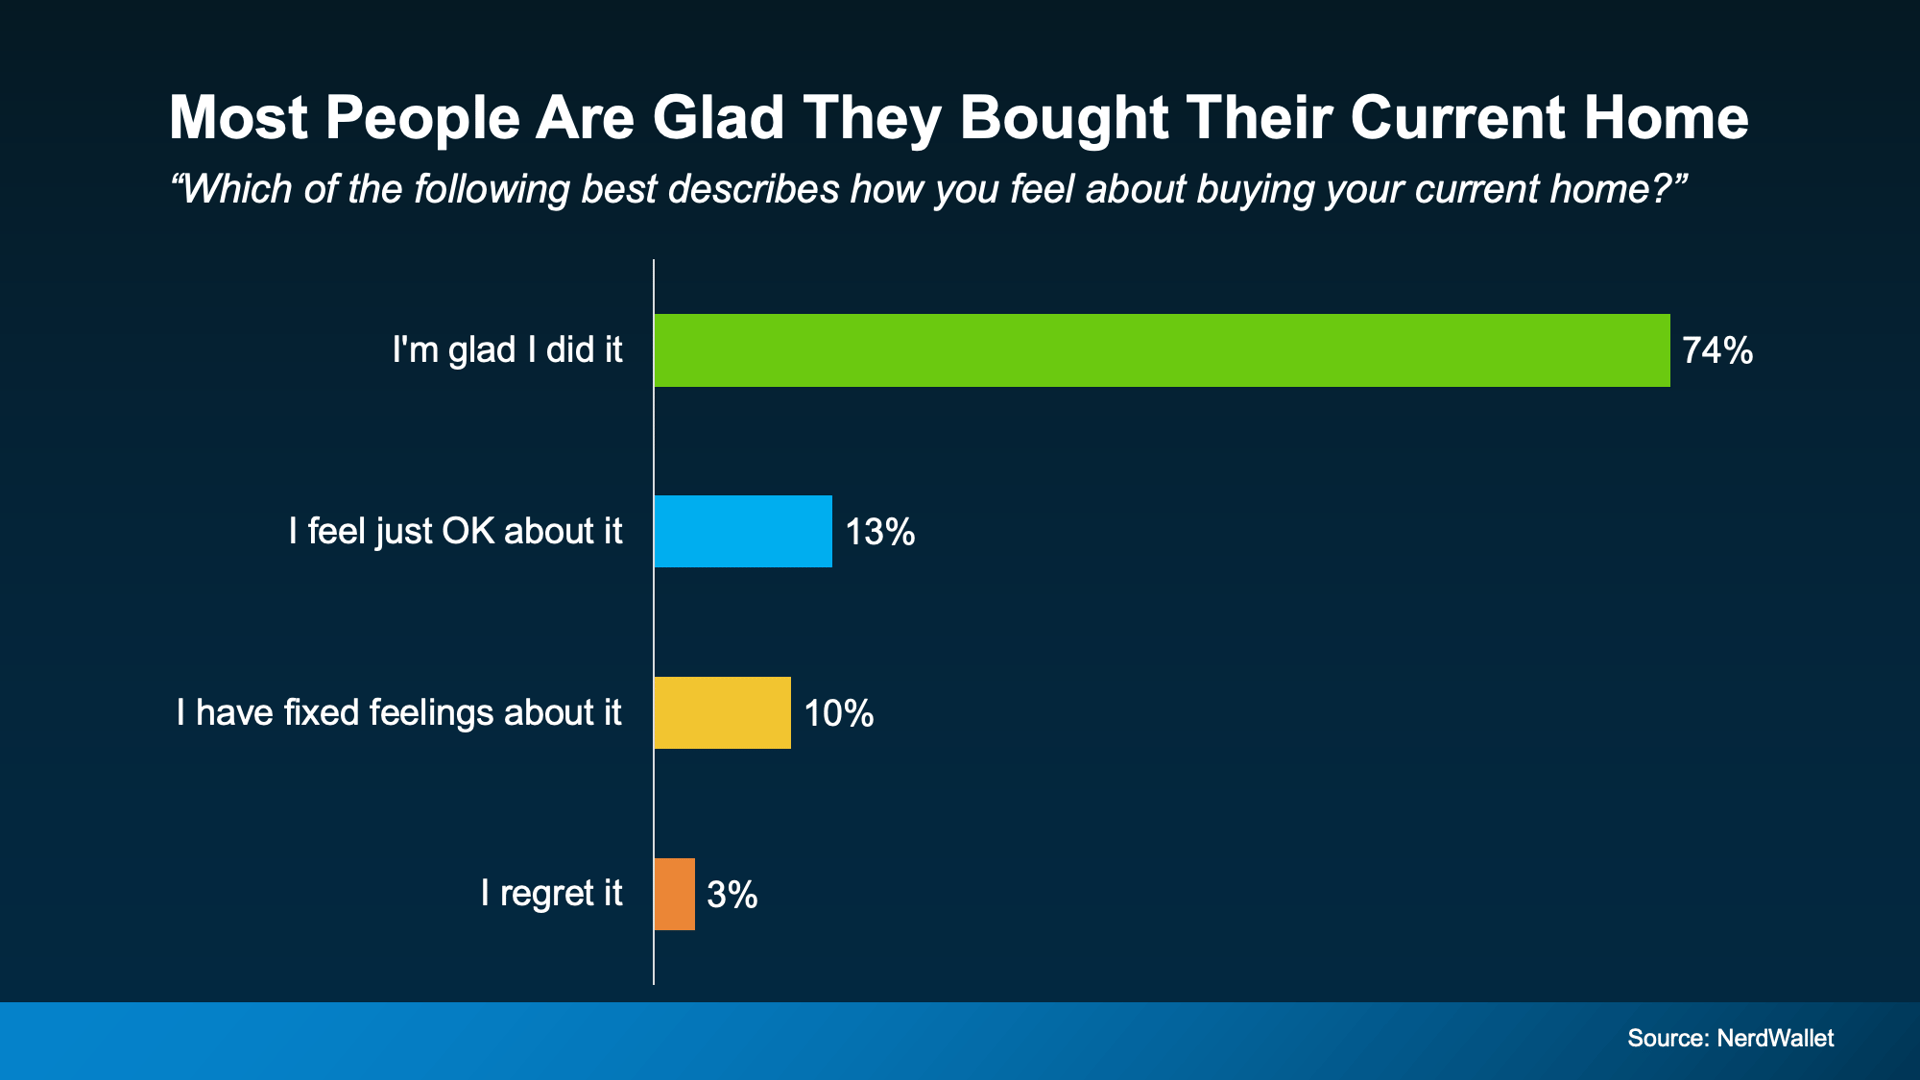
The survey doesn't mean every home purchase turns out perfectly. Some homeowners may have mixed feelings, and others may be dealing with unexpected challenges.
But it does suggest that for many Americans, the benefits of owning a home outweigh the challenges.
And one of those benefits is the opportunity to build wealth over time.
Let's bring this home to Tallahassee.
According to Florida Realtors® SunStats, the Tallahassee Metropolitan Statistical Area recorded a median single-family home sale price of $329,950 in September 2026, down 5.7% from $349,950 in September 2025.
That's a noticeable change.
But does that mean every home in Tallahassee lost 5.7% of its value over the past year?
Not necessarily.
Median sale prices reflect the homes that actually sold during a particular period. If more lower-priced homes sell one month, or the mix of properties changes, the median can shift without representing an equivalent change in the value of individual homes.
For a longer-term perspective, we can look at the Federal Housing Finance Agency's House Price Index.
According to FHFA data published through the Federal Reserve Bank of St. Louis, the Tallahassee metro area's All-Transactions House Price Index increased approximately 43% between the second quarter of 2021 and the second quarter of 2026.
That's a substantial increase over five years, even as the local market has experienced periods of changing demand, affordability concerns, and shifting prices.
The difference matters. A decline in the median price of homes sold in a single month doesn't necessarily mean the market has lost the appreciation accumulated over several years.
The latest local housing statistics also offer some useful perspective for people considering a purchase today.
In September 2026, the Tallahassee single-family housing market recorded:
These numbers don't tell us that every home is a bargain, or that every seller is willing to negotiate.
What they do tell us is that Tallahassee's market has changed.
Homes that went under contract during September did so more quickly than a year earlier, even as the number of newly pending sales declined significantly. Inventory remains available, and sellers are not universally receiving their original asking prices.
For buyers, that makes understanding the specific neighborhood, price range, property condition, and comparable sales especially important.
A well-priced home in desirable condition may attract attention quickly. Another property may offer more room to negotiate.
Rather than trying to time the entire Tallahassee housing market, it may make more sense to focus on finding the right home at a price and monthly payment that work for you.
Looking beyond Tallahassee, the national picture reinforces why homeownership is often considered a long-term financial decision.
According to the FHFA's second-quarter 2026 House Price Index data, national home prices increased approximately 33.4% over the previous five years.
In Florida, that five-year increase was approximately 37.5%.
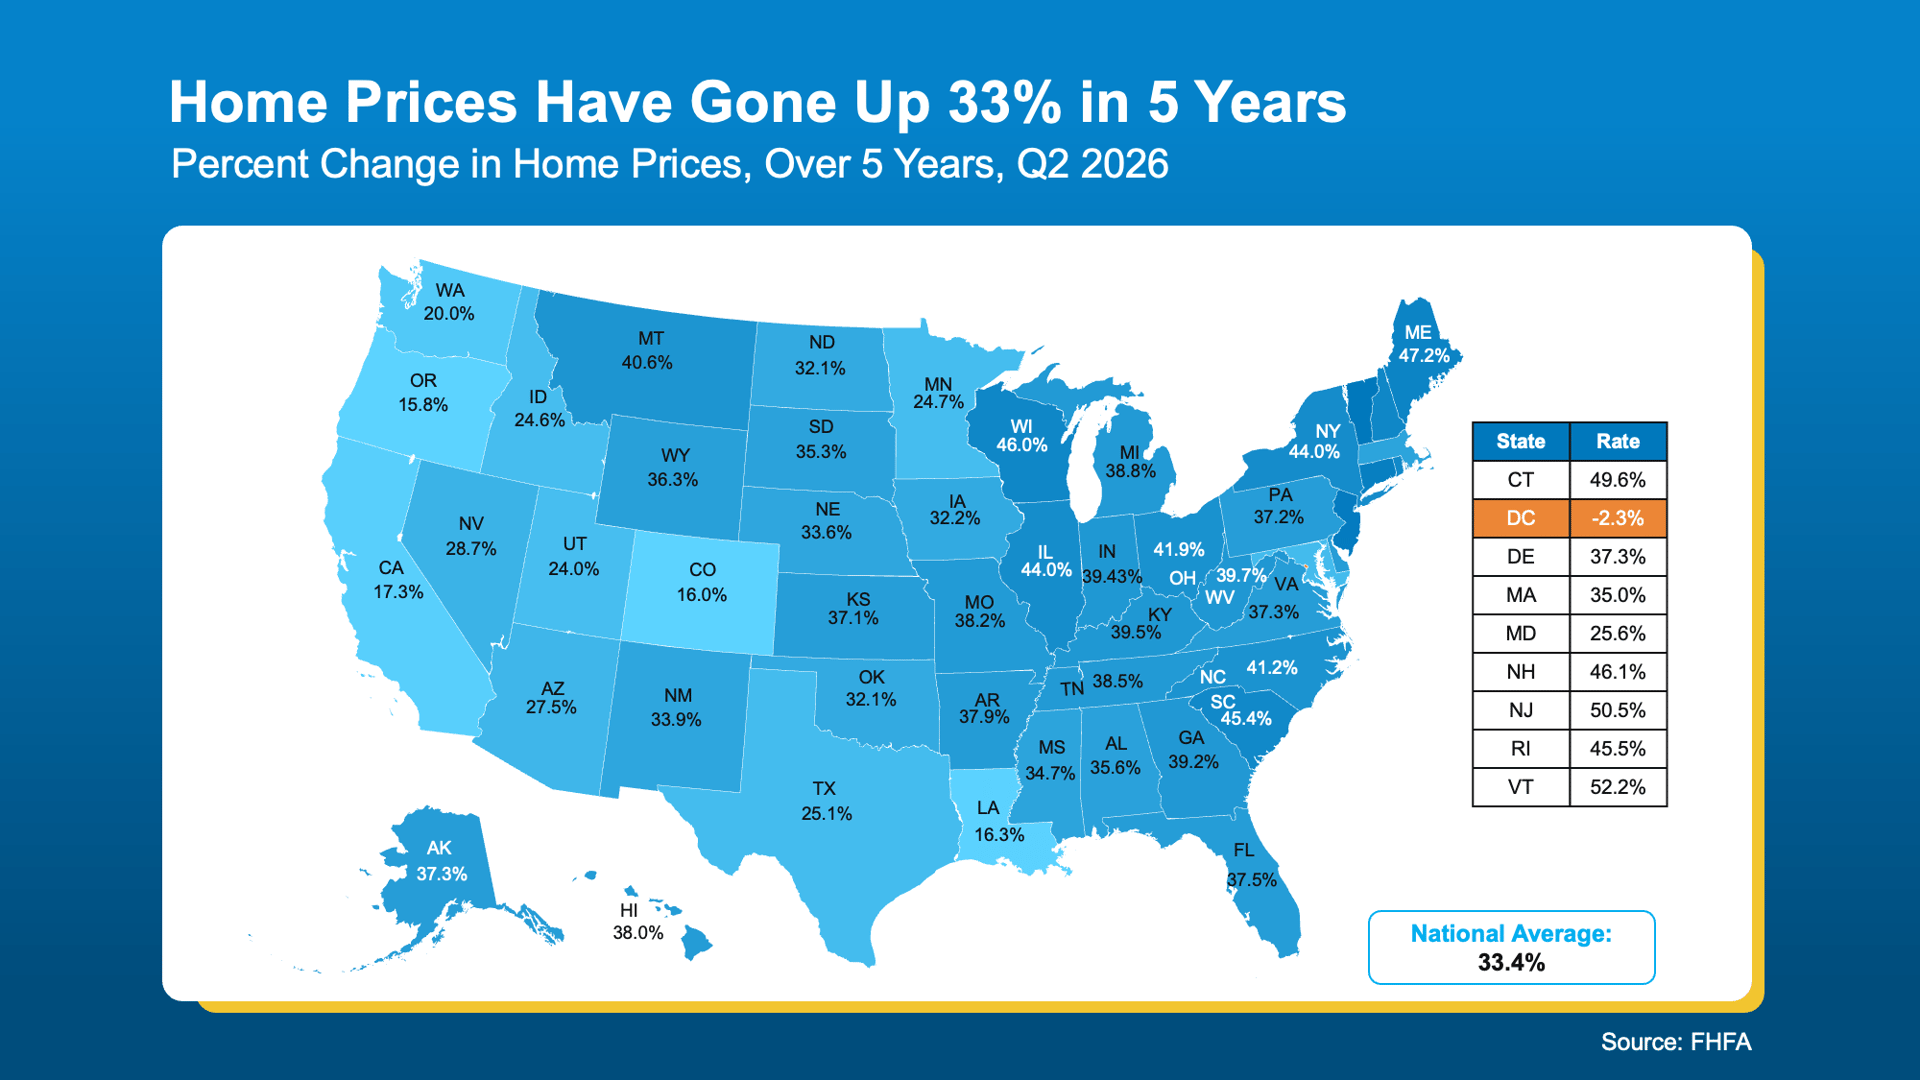
These figures come from the FHFA's purchase-only, seasonally adjusted index, which uses a different methodology from the Tallahassee all-transactions index discussed above. While the figures aren't directly interchangeable, both demonstrate how much home values have changed over the longer term.
And appreciation isn't the only way homeowners may build wealth.
When you make payments on a traditional amortizing mortgage, part of each payment generally goes toward reducing the principal balance. Over time, that can increase your ownership stake in the property.
That stake is called equity.
Home equity is generally the difference between what your home is worth and what you still owe on it.
According to the National Association of REALTORS®, the typical U.S. homeowner accumulated approximately $147,000 in housing wealth over a five-year period.
Of course, that's a national estimate, not a guarantee of what someone purchasing a home in Tallahassee will experience. Individual results depend on purchase price, financing, market conditions, expenses, and how long the property is owned.
Still, it demonstrates why homeownership can be an important part of long-term financial planning.
Five years can make a significant difference. But what about 10, 20, or even 30 years?
According to the FHFA, national home prices increased approximately 336% between the first quarter of 1991 and the second quarter of 2026.
Florida's increase over that period was approximately 447%.
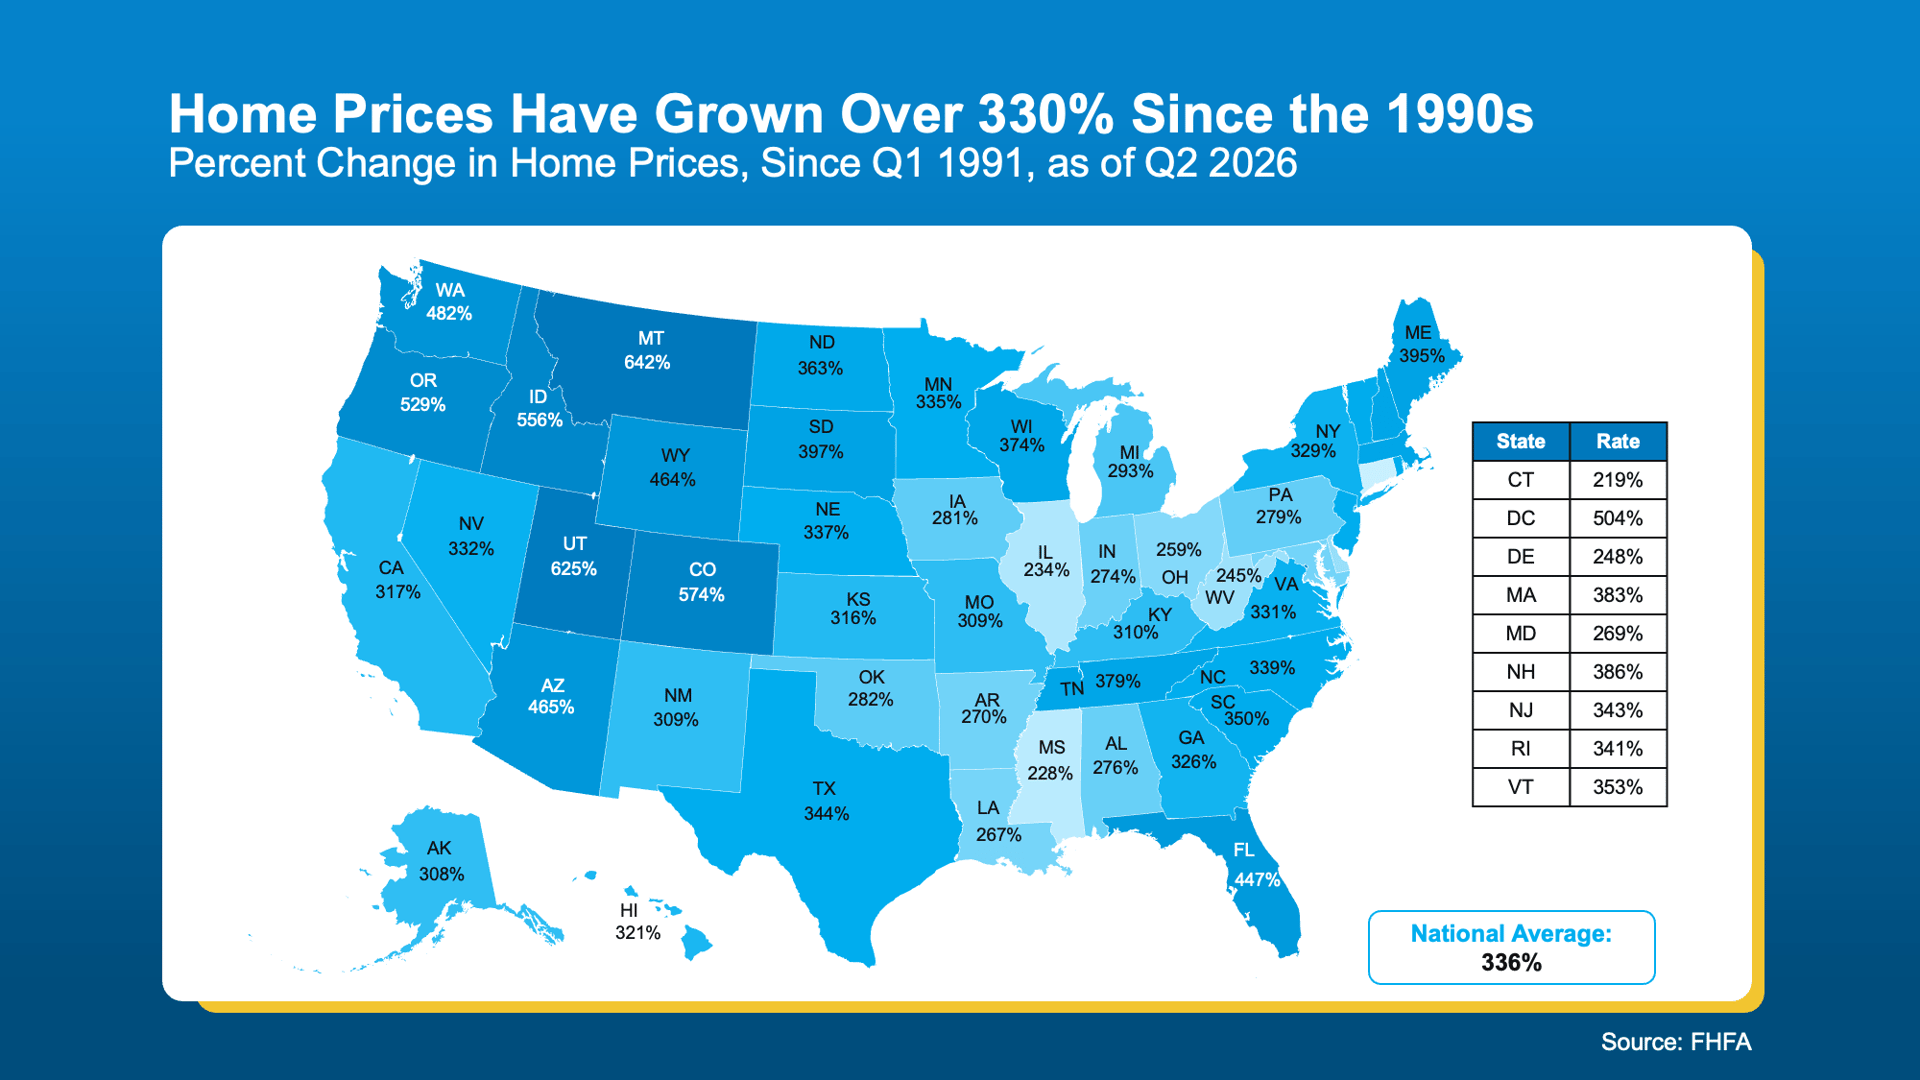
Those are substantial changes, although the figures are not adjusted for inflation and don't account for the ongoing expenses of homeownership.
And there's another important detail: those increases did not happen in a straight line.
Home values have experienced downturns, including the housing market crash associated with the Great Recession. Some markets have also experienced periods of stagnant or declining prices.
But looking at several decades of data helps explain why homeownership is generally better evaluated as a long-term decision than a short-term investment.
A home purchased today could increase in value over time. It could also experience periods when its market value declines.
The longer you plan to own the property, the more opportunity you may have to navigate those changes. That doesn't eliminate the risks, but it can change how you evaluate them.
For someone who already owns a home in Tallahassee, accumulated equity may provide opportunities that weren't available when they first purchased.
Depending on the property's current value, outstanding mortgage balance, and selling expenses, that equity could potentially help fund the down payment on another home, support a move to a different property, or contribute toward other financial goals.
For someone purchasing their first home, the opportunity to build equity begins with ownership.
As Freddie Mac explains, equity becomes part of a homeowner's overall wealth and may provide financial flexibility when it's time to move.
That doesn't mean a house should be treated like a guaranteed investment.
Property taxes, homeowners insurance, interest, maintenance, repairs, and transaction expenses all affect the actual cost of ownership. And accessing equity through borrowing introduces additional debt and financial obligations.
But when the numbers make sense, homeownership may provide both a place to live and an opportunity to develop a valuable financial asset.
Here's where things become personal.
If you're planning to move again in a year or two, purchasing a home may not make financial sense, particularly after considering closing costs and the potential expense of selling.
If your monthly payment would stretch your finances too thin, waiting may be the better decision.
And if you're hoping mortgage rates or home prices will improve, there's nothing wrong with carefully evaluating your options.
But there's also a risk in waiting for the perfect combination of prices, mortgage rates, and market conditions.
Nobody knows exactly where Tallahassee home prices or mortgage rates will be a year from now.
The more useful questions might be whether you can comfortably afford the home, whether it meets your needs, how long you expect to stay, and how the costs compare with your alternatives.
You don't necessarily have to buy at the absolute bottom of a market for homeownership to become a worthwhile long-term decision.
And you certainly shouldn't buy simply because someone tells you home prices always go up.
If you're worried about regretting a home purchase, the numbers offer some perspective.
Most Americans surveyed by NerdWallet are glad they purchased their current homes. FHFA data shows substantial home price appreciation nationally, across Florida, and in the Tallahassee metro area over the longer term.
Meanwhile, September 2026 market statistics show that Tallahassee's housing market is offering a different set of conditions than it did a year ago.
The goal isn't necessarily to buy at the perfect time. It's to make a decision that makes sense for your finances, your lifestyle, and your future.
Stay up to date on the latest real estate trends.
All Real Estate News
October 20, 2026
Articles for Buyers
October 19, 2026
October 19, 2026
All Real Estate News
October 17, 2026
All Real Estate News
October 16, 2026
All Real Estate News
October 15, 2026
You’ve got questions and we can’t wait to answer them.