What Is a Home Appraisal?
January 18, 2026
Articles for Sellers
January 18, 2026
Articles for Sellers
This article provides general information based primarily on the Tallahassee Board of REALTORS® Contract for Sale and Purchase, revised March 2026. Individual transactions may involve different contracts, amendments, addenda, or statutory requirements. This article is not legal advice. Consult a Florida real estate attorney regarding specific contractual rights or disputes.
You've agreed on a price for a home. But how do you know what it's actually worth?
That's where a home appraisal comes in.
Whether you're selling, buying, or refinancing a home in Tallahassee, an appraisal can play an important role in determining how much a lender is willing to finance.
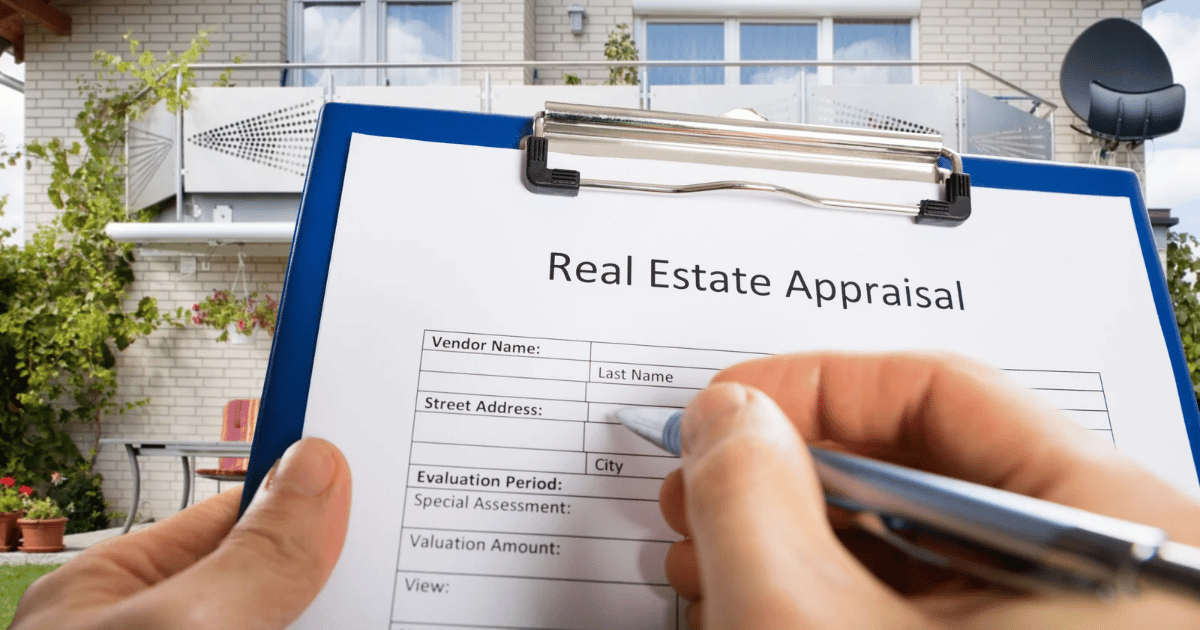
A home appraisal is an independent, professional opinion of a property's market value. It's typically completed by a state-licensed or certified real estate appraiser who evaluates the home, its characteristics, and comparable properties in the surrounding market.
While an appraisal is an important part of many real estate transactions, it's not the same as a home inspection, a real estate agent's market analysis, or the estimated value you might see online.
Understanding how appraisals work can help sellers price their homes appropriately, help buyers make informed decisions, and prevent surprises before closing.
Quick Links: Why Is an Appraisal Needed? | How Does an Appraisal Work? | What Determines Value? | Appraisal vs. Inspection | Low Appraisals | Tallahassee Contract | Preparing for an Appraisal | Bottom Line
When a home is purchased using mortgage financing, the lender generally needs to determine whether the property provides sufficient value to support the loan.
An appraisal helps answer an important question: Does the home's estimated market value support the agreed-upon purchase price?
For example, if a home is under contract for $350,000, the lender may request an appraisal to determine whether the property supports that value.
Appraisals help lenders evaluate their financial risk, but they can also provide valuable information to sellers and buyers about the property's position in the market.
The appraisal is typically ordered through the buyer's lender, with the buyer generally responsible for the cost. Some loan programs and circumstances may allow lenders to use alternative valuation methods or waive a traditional appraisal.
Cash transactions don't ordinarily require a lender's appraisal, although the parties may choose to obtain one.
Once an appraisal is ordered, the appraiser gathers information about the property and analyzes relevant real estate market data.
Depending on the assignment and lender requirements, this may involve an interior and exterior property visit, an exterior-only evaluation, or another approved valuation process.
The appraiser reviews the home's characteristics, researches comparable sales, and considers differences between the property and others that have recently sold.
The completed appraisal report provides an opinion of value as of a specific date, along with information supporting that conclusion.
Unlike a listing price, which a seller can establish based on their goals and market strategy, an appraisal must be supported by the appraiser's independent analysis.
One of the most important parts of an appraisal is the sales comparison approach, which examines properties that have recently sold and are reasonably comparable to the home being evaluated.
According to Fannie Mae's appraisal guidelines, comparable properties should have similar physical and legal characteristics, and appraisers must account for relevant differences.
Factors that may influence a home's appraised value include:
For example, a recently renovated home in Tallahassee might be compared with similar nearby properties that have sold in different conditions. The appraiser may adjust those sales to account for differences supported by market evidence.
However, the amount spent on an improvement doesn't necessarily equal the value it adds. A $30,000 kitchen renovation may not increase a home's appraised value by $30,000.
Market conditions matter, too. If comparable homes have recently sold at lower prices, an appraisal may reflect those transactions even when a seller believes their home should command more.
Local market knowledge is especially important in Tallahassee, where nearby neighborhoods can have very different property characteristics and market values.
For example, an appraiser should understand how the historic architecture, larger homes, and distinctive character of Los Robles may influence value differently than the smaller cottages, bungalows, and lots commonly found in Levy Park, rather than relying on proximity alone when selecting comparable sales.
It may be worth asking how familiar the appraiser is with the local area.
These services may involve evaluating the same property, but they serve different purposes.
Appraisal: An independent opinion of market value prepared by a qualified appraiser, often for mortgage lending purposes.
Home Inspection: An evaluation of the property's physical condition, intended to identify defects, maintenance concerns, and items that may require further attention. An appraisal is not a substitute for a home inspection, although an appraiser may identify conditions affecting value or loan eligibility.
Comparative Market Analysis (CMA): An evaluation prepared by a real estate professional using comparable sales, active listings, and market conditions to help sellers establish an asking price or buyers evaluate an offer.
Online home value estimates and property tax assessments are also different from formal appraisals. These estimates may be useful reference points, but they can rely on different information, assumptions, and valuation methods.
Sometimes, the amount someone agrees to pay for a home is higher than the appraised value.
For example, suppose a Tallahassee home is under contract for $350,000, but the appraisal comes back at $340,000.
That's a $10,000 appraisal gap.
Because lenders commonly calculate financing based on the lower of the purchase price or appraised value, this difference may affect the amount the buyer can borrow.
Depending on the financing and contract terms, several outcomes may be possible. The buyer might contribute additional funds, the seller might agree to a price reduction, or the parties could negotiate another arrangement.
If the appraisal contains factual errors or overlooks relevant comparable sales, the borrower may also request a reconsideration of value through the lender.
Importantly, a low appraisal does not automatically require the seller to lower the purchase price. The parties' rights and options depend on the contract and applicable financing requirements.
If a home appraises above the purchase price, the agreed purchase price doesn't automatically increase either. The parties remain subject to their contract.
The Tallahassee Board of REALTORS® Contract for Sale and Purchase includes specific appraisal provisions.
For new third-party financing, if the appraisal is below the purchase price or requires repairs that conflict with, or are not addressed in, the agreement, the buyer must notify the seller and provide a complete copy of the appraisal within two days of receiving it.
The seller then has three days after receiving the appraisal to notify the buyer in writing if the seller declines to proceed at the appraised amount and terms.
Importantly, failing to respond within that three-day period is considered acceptance under the contract.
If the seller declines, the buyer generally has two days after receiving that notice to proceed despite the appraisal or terminate under the applicable provisions.
Additional provisions may apply to FHA, VA, and other financing arrangements.
The local contract also addresses appraisals in cash and seller-financed transactions when the applicable option is selected it typically gives the buyer a five-day appraisal-ordering period and a waiver, if not ordered on time.
Because appraisal provisions can significantly affect a transaction, sellers and buyers should carefully review their specific contract, deadlines, and any addenda.
While sellers cannot control an appraiser's independent opinion, they can help ensure accurate information about the property is available.
Before the appraisal, it may be helpful to complete routine maintenance, provide reasonable property access, and gather documentation of improvements, permits, and significant repairs.
Your real estate agent may also provide relevant property information and comparable sales for the appraiser to independently review.
The goal isn't to influence the appraiser's conclusion. It's to make sure the property's characteristics and improvements are accurately represented.
For sellers, preparing for the appraisal begins even earlier with a pricing strategy supported by local market data.
A home appraisal is an important part of many Tallahassee real estate transactions because it provides an independent opinion of a property's market value.
For sellers, understanding how appraisals work can help with pricing and evaluating offers.
For buyers, an appraisal helps determine whether the property's value supports the proposed financing.
And while an appraisal may create challenges when it differs from the purchase price, it doesn't necessarily mean the transaction can't move forward.
Because understanding what a home is worth is important. Knowing how to navigate the transaction is just as valuable.
This article provides general information based primarily on the Tallahassee Board of REALTORS® Contract for Sale and Purchase, revised March 2026. Individual transactions may involve different contracts, amendments, addenda, or statutory requirements. This article is not legal advice. Consult a Florida real estate attorney regarding specific contractual rights or disputes.
Stay up to date on the latest real estate trends.
All Real Estate News
November 3, 2026
All Real Estate News
November 2, 2026
All Real Estate News
November 2, 2026
All Real Estate News
October 31, 2026
All Real Estate News
October 30, 2026
All Real Estate News
October 29, 2026
You’ve got questions and we can’t wait to answer them.